Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
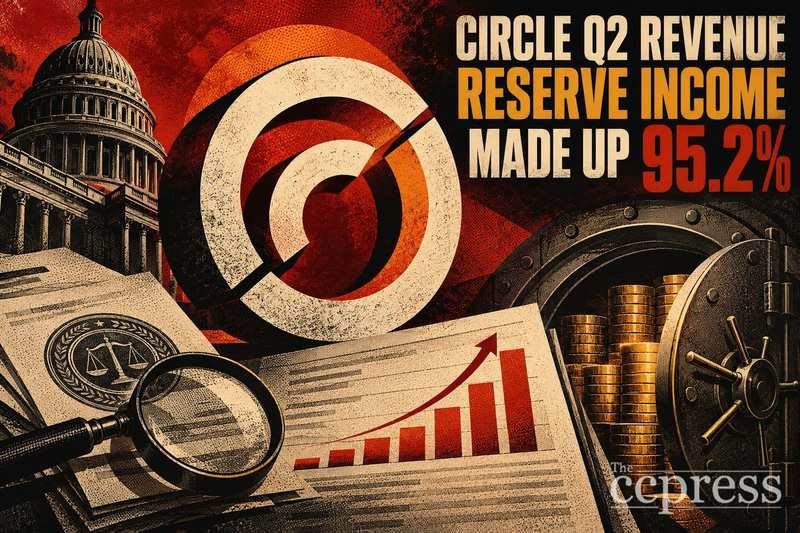
Circle's second-quarter revenue: Reserve income accounted for 95.2%
Almost every dollar Circle earned in the second quarter came from a single channel: interest generated on assets that support USDC (USD Coin). Reserve income accounted for 95.2% of Circle's total revenue in the second quarter, a data that clearly reveals the fact that the financial health of stablecoin issuers is highly tied to the yield environment of their collateral.
For Circle, issuing USDC itself is not its core business; holding and managing the reserves that support USDC is its real business model. This distinction becomes crucial when interest rates fluctuate.
When one revenue line dominates the entire income statement
When stablecoin issuers collect dollars from users and issue tokens in return, these funds are not idle. They are invested in short-term assets, usually U.S. Treasury bonds and money market instruments, and the returns on these assets become the main source of income for issuers. At 95.2% of total revenue, reserve income is not only Circle's largest source of revenue, but is actually a key factor in determining individual quarterly performance.
This concentration makes Circle's results extremely sensitive to top-level expectations, which is completely different from the situation of most fintech companies. When more than one-nineteenth of a business's revenue comes from a single revenue line, the company's fate is largely determined by the macro financial environment before any operating decisions are made.
Why supporting assets determine the fate of issuers
储备收益率与稳定币发行商收入之间的关系直接且有据可查。分析指出,美联储的同一项利率决策既可能给比特币借贷者带来压力,同时又能提升稳定币发行商的收益,因为更高的利率会立即转化为填充储备投资组合的短期资产的高收益。
Circle已明确采用这一模式。该公司最近为机构客户推出了以比特币为支持的USDC贷款,扩展了其利用接近储备的活动的方式,尽管核心的盈利引擎仍然是抵押品本身。
逻辑的另一面则是风险。如果利率下降,储备收益率就会压缩,而95.2%的集中度意味着整个损益表将随之收缩。目前并没有第二支柱来缓冲这种下跌。
通过单一比率解读Circle的业绩
当几乎所有报告的收入都追溯到一个变量时,季度结果就成为了衡量利率政策而非运营执行能力的代理指标。交易量增长、新链部署和合作伙伴关系宣布对于长期的供应扩张至关重要,但在储备基础与之同步增长之前,它们并不能独立产生大规模的营收。
Circle has been building infrastructure that could ultimately diversify the situation. The launch of Arc Mainnet, including the participation of verification nodes such as BlackRock, DTCC and Visa, points to a settlement and infrastructure layer built on a reserve income model. The core question for investors and analysts is whether this layer can generate revenue of sufficient size to significantly reduce concentration by 95.2%.
The broader regulatory environment introduces another variable. Leadership changes, such as the departure of Sean Neville from Circle's board and the trend of competitors seeking banking licenses, suggest the industry is still exploring what the best structure for supporting issuers might look like.
For now, the 95.2% figure gives a straightforward answer: Circle's core is essentially an interest rate transaction wrapped in a payment product. How this ratio will evolve in a low-interest-rate environment will be a key story that defines its next stage of financial performance.