Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
Key facts: The definition of income distribution in the U.S. stablecoin Act
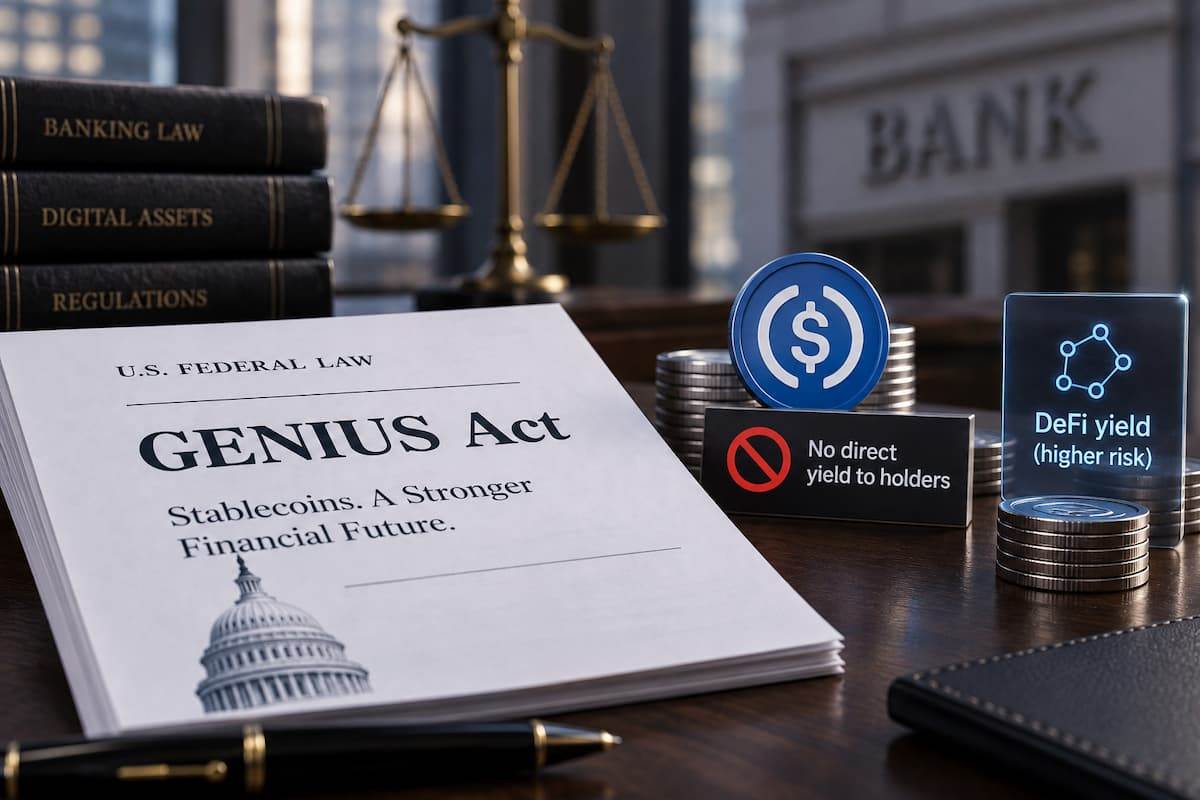
With the formal passage of the GENIUS Act as a U.S. stablecoin regulatory law, it clearly stipulates that issuers of stablecoins shall not directly pay interest or income to holders. As a result, banks that are exploring issuing stablecoins are turning their attention to interest-bearing strategies on reserves or balances themselves.
Directing these balances into decentralized finance (DeFi) protocols effectively transfers smart contract risk and liquidity risk to those participants exposed to underlying revenue strategies.
Legal boundaries and substantive differences
The federal stablecoin framework established by the GENIUS Act has drawn a clear boundary, which has profoundly influenced banks 'current exploration of stablecoin revenue models: issuers cannot directly pay interest or income to users just because they hold tokens. The restriction is designed to prevent stablecoins from turning into inadequately regulated bank deposits, which could improperly compete with traditional accounts that enjoy insurance protection. Literally speaking, this rule is very clear.
What the law does not fully clarify, however, is what happens when banks or their partners channel the reserves or balances supporting stablecoins into interest-bearing strategies (including decentralized financial agreements) rather than paying benefits directly to holders?
There is a substantive difference here: what is prohibited by law is "the issuer of a stablecoin paying interest to the holder", but for the behavior of "the issuer or downstream platform to earn income from the assets that support or package the stablecoin", its regulatory status depends on the design of the specific architecture and is in a relatively vague area.
For example, a bank cannot advertise "holding our stablecoins and enjoying a 4% yield." However, if a stand-alone DeFi agreement based on a stablecoin issued by the same bank provides lending or liquidity products and happens to use the stablecoin as the underlying asset, this is a structurally different arrangement. Although the actual experience may be almost the same for end-users seeking revenue, the legal characterization is quite different.
Risk transfer and concealment
The real risk transfer occurs here, and when news headlines only focus on yield percentages and ignore underlying structures, this part is often ignored.
Banks 'own deposits are protected by insurance under statutory limits and backed by capital requirements accumulated over decades of banking regulation. In contrast, the DeFi protocol, which provides stablecoin benefits, does not have these safeguards; it carries smart contract risks (i.e., code flaws can lead to permanent loss of funds) and liquidity risks (i.e., the protocol may not be able to meet withdrawal obligations during stress events).
Users who pursue revenue on bank-issued stablecoins through DeFi encapsulation do not get "bank-level security plus DeFi-level returns", but "DeFi-level risk disguised as bank reputation."
Why this gap is expected to widen rather than narrow
As more banks explore stablecoin issuance under the GENIUS Act, commercial impetus is prompting them to retain an interest-bearing mechanism outside of their regulatory scope: close enough to take advantage of banks 'brand reputation and reserve support, but far enough to avoid legal restrictions on direct payment gains. This business incentive will not disappear.
A practical revelation for any participant evaluating stablecoin-based income products is that the bank name behind the stablecoin does not explain the security of its upper-level income mechanism. These two need to be evaluated as two separate issues and cannot be confused.