Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
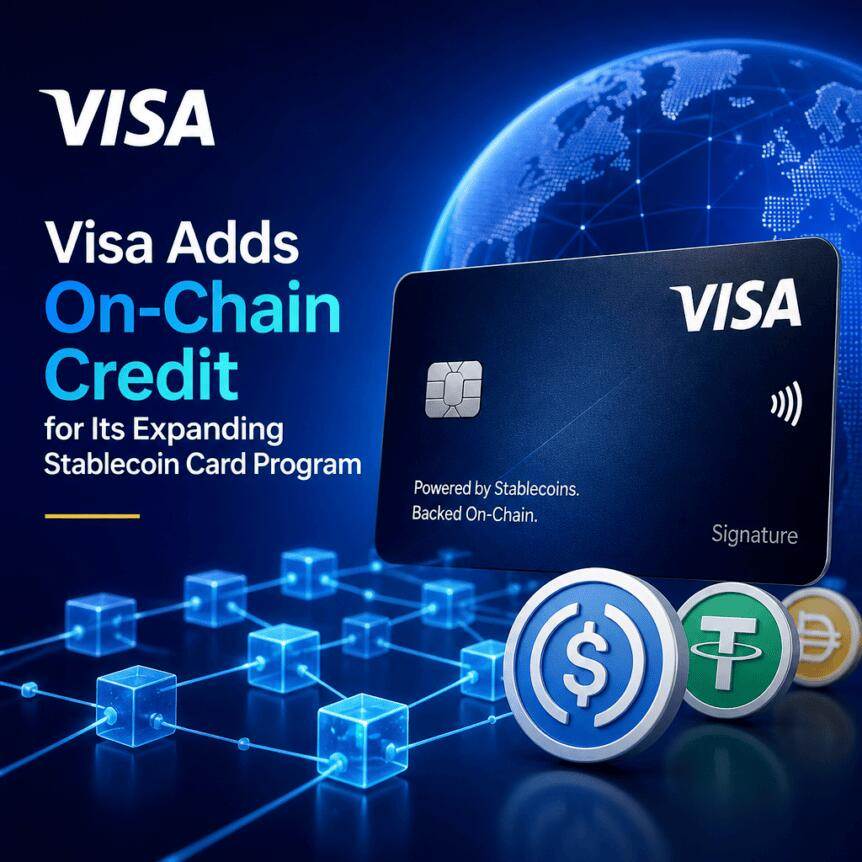
Visa launches a new blockchain-based settlement data credit model
Visa recently announced a new corporate financing method that connects its payment settlement records with a blockchain-based lending system. The payments giant said the move aims to allow lenders to combine VisaNet settlement data with on-chain transaction information to evaluate borrowers and issue credit against payment obligations-which effectively integrates on-chain lending more closely into daily payment processes.
The announcement, released on Tuesday, positions the stablecoin-linked card program and on-chain credit as part of the broader payment infrastructure. In this architecture, settlement data can serve as a signal source for "working capital" rather than relying solely on traditional bank-style documentation.
Core Points
- Data Fusion: Visa will combine VisaNet settlement data with blockchain lending infrastructure to use off-chain settlement records and on-chain activities to jointly provide financing support for companies 'payment obligations.
- Early Cases: Credit Coop As an early example, cumulative settlements reported in participating facilities since 2023 have exceeded US$2.5 billion.
- Network growth: Visa said its stablecoin-linked card network has expanded to more than 160 projects, with payments increasing by nearly 200% year-on-year.
- Settlement scale: According to Visa, stablecoin settlement volume has reached an annualized operating rate of US$20 billion.
This move marks a strategic shift: On-chain lending is expected to expand from a model dominated by cryptocurrency native collateral to the payment and settlement ecosystem.
Operating mechanism for Visa's settlement-linked lending model
Visa pointed out that the initiative will connect data generated by its settlement network with a blockchain-based lending system. In practice, lending institutions can juxtapose Visa settlement records with blockchain transaction data to evaluate borrowers and decide whether to provide financing for their settlement obligations.
Visa believes that settlement information is at the core of payment execution. By enabling this information to be used in blockchain lending workflows, lending institutions have the potential to shorten the time lag between payment authorization or processing and conversion into credit.
Although the company does not describe a single universal lending mechanism, the core concept is clear: settlement results can serve as a useful data layer for on-chain Underwriting, thereby reducing the friction caused by traditional credit decisions relying on independent document sources.
Early case: Credit Coop's settlement financing
To illustrate this concept, Visa mentioned Credit Coop, a blockchain-based protocol that provides credit lines to businesses. Visa said that since 2023, Credit Coop has raised more than $2.5 billion in cumulative settlements in participating facilities.
Visa added that the project involved more than 3,000 borrowing events and 9,000 repayments. Although these data are not a direct measure of credit performance across the Visa ecosystem, they do provide a specific indicator that credit linked to settlement has been running on the chain at a meaningful scale for quite some time.
What is relevant for market participants is the direction Visa is trying: The system no longer limits its credit model to token-native lending against crypto-assets, but instead connects lending eligibility to payment settlement signals-which promises to expand the accessible borrower base to merchants and business use cases related to card and stablecoin tracks.
Visa lays the foundation for broader stablecoin expansion
This push for settlement-linked lending comes as Visa continues to deepen its stablecoin strategy. During Visa's third-quarter earnings conference call in July, management said the company was "investing in every layer of the stable coin stack", covering blockchain, wallets, infrastructure and applications. The company also describes stablecoins as a force in changing the way money flows and creating opportunities to rethink payment infrastructure.
Growth in Visa stableco-related business is also reflected in card item and settlement data. Visa pointed out that it currently operates more than 160 stableco-linked card projects on its network, and payment volume has increased by nearly 200% year-on-year.
In terms of specific settlement activities, Visa said that its stablecoin settlement volume has exceeded the annualized operating rate of US$20 billion. The company also claims that the figure is more than 15 times higher than the level of the same period last year-a sign that stablecoin payments are moving from the experimental phase to higher-volume operating activities within Visa's orbit.
The key point for readers who are concerned about the impact of on-chain lending is that Visa seems to view stablecoin settlement as both a payment use case and a data basis. As settlement volumes grow, the underwriting inputs potentially available to lenders in the same payment-driven ecosystem will also increase.
stablecoin trading volumes continue to rise, but underwriting links are the key bet
Visa's own data analysis points to the continued momentum of stablecoin transfers. According to Visa's analytical dashboard, adjusted stablecoin trading volume hit a record of $1.79 trillion in June, and trading volume in the past 30 days has been approximately $1.2 trillion.
These totals highlight the overall market demand for stablecoin settlement. However, Visa's new lending concept is essentially betting on something more specific than usage: that payment settlement data can be integrated into lending infrastructure in a way that improves corporate credit decisions and liquidity acquisition.
This distinction is crucial. Growth in stablecoin transfers alone cannot automatically translate into viable credit products. Visa's initiative aims to bridge this gap by transforming settlement records into potential underwriting inputs and layering them into blockchain-based lending facilities.
Visa also mentioned its participation in the OpenStandard Alliance, which plans to issue OpenUSD stablecoins and has more than 140 participating companies. While this effort is separate from settlement-linked lending, it highlights the multiple ways Visa is strengthening the stablecoin ecosystem around its payment network.
Future Outlook
The next phase may be less announced and more practical deployment: to what extent lending methods linked to settlement will be widely adopted, which lending facilities will integrate VisaNet settlement data, and whether lending institutions can use payment settlement signals to expand underwriting without sacrificing risk control.
As stablecoin-linked card projects and settlement volumes grow, the real test will be whether on-chain lending will become the standard financing layer for payment-driven companies, rather than just a niche add-on feature.