Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
 BTC
 ETH
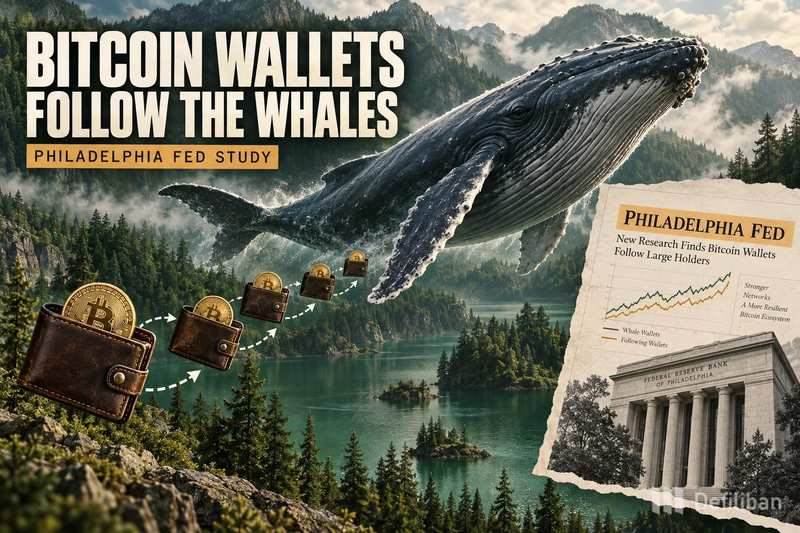
Philadelphia Fed Working Paper: Analysis of Market Reaction after Bitcoin Whale Trading
A working paper from the Philadelphia Fed pointed out that Bitcoin wallets are more likely to follow the whale's trading direction within 15 minutes of a public "whale"(large holder) alert. This co-directional response gradually waned and returned to baseline within an hour, while on Ethereum it had little significant impact.
This discovery is one of the core elements of the controversy surrounding the Bitcoin whale trade. This conclusion is based on a preliminary event study method that describes changes in the participation shares of different wallet groups, rather than verifying the documentary trading behavior of individual holders.
Key Points
- Philadelphia Fed Working Paper 26-42 pointed out: Shortly after the public alert was issued, the non-whale fish Bitcoin wallet community was more inclined to follow the whale's trading direction.
- Reaction Time Window: The strongest reactions occur in the first 15 minutes of the public alert and reach normal levels within 60 minutes.
- The nature of the study explains: This paper is a preliminary observational study; the estimated data reflect the changes in the participation share of each wallet group, and does not prove that the trader has engaged in the behavior of copying whale operations.
Details of Philadelphia Federal Reserve's report on Bitcoin whale trading
The discovery comes from Philadelphia Fed Working Paper No. 26-42, entitled "How can large and complex cryptocurrency transactions affect broader decentralized finance (DeFi) market dynamics?" Written by Keith Hazen, Julapa Jagtiani and Loretta J. Mester, released in September 2026.
The same direction trading pattern in the report
The study used publicly transmitted whale alerts as an event clock to measure whether non-whale wallets subsequently traded in the same direction. In a full-sample Bitcoin regression analysis, data related to whale buy alerts showed that in the first 15 minutes, buying participation in the three categories of non-whale wallets increased by 14.81 percentage points and 23.72 percentage points and 3.50 percentage points respectively, all results were significant at the 1% level.
Bitcoin Whale Buy Alert: Mid-sized wallet participation increased by 23.72 percentage points
In the first 15 minutes after the public alert was issued, full-sample regression showed an estimated 23.72 percentage points increase in buying participation for mid-sized non-whale wallets (significant at the 1% level). Note that this is a change in group participation shares, not individual probability or token return; this association does not establish causality.
A similar pattern was also shown on the selling side. After the Bitcoin Whale Sell Alert, estimates for the first 15 minutes were 12.95, 29.52 and 2.95 percentage points for small, medium and large wallets, respectively, which were significant at the 5%, 1%, and 5%, respectively. Again, these are changes in group participation shares rather than individual probabilities or token returns.
Bitcoin Whale Sell Alert: Mid-sized Wallet Participation Increase by 29.52 percentage points
In the first 15 minutes after the public alert was issued, full-sample regression showed an estimated increase in selling participation for mid-sized non-whale wallets by 29.52 percentage points (significant at the 1% level). Note that this is a change in group participation shares, not individual probability or token return; this association does not establish causality.
The 15-minute window and its triggering mechanism
The trigger that initiates the timing is a public dissemination of the "whale alert" notification, rather than a private data feed. The raw Bitcoin directional response was strongest during this first 15-minute window and decayed to normal levels within 60 minutes. This short half-life suggests that this is a response to an open signal rather than a lasting structural transformation.
Ethereum's performance is different. The paper points out that Ethereum's immediate directional response is largely missing and appears only among the largest investors in the sell model, with an estimated value of 0.76 percentage points. The article also notes that this difference between Bitcoin and Ethereum continues after Ethereum switched from Proof of Work (PoW) to Proof of Equity (PoS) on September 15, 2022.
Implications for wallet behavior by this reporting model
The authors view this result as a signal of market structure. In their summary, Hazen, Jagtiani and Mester wrote that the results suggest persistent information and structural asymmetry between large and small digital asset investors. This is an explanation rather than an independent regulatory conclusion.
Co-trade does not establish intention
Groups following the whale's direction to trade after an alert are a correlated phenomenon rather than an observed evidence of a decision to duplicate trade. Incident study methods cannot confirm whether any wallet operator saw the alert. In addition, since the "whale" status here is based on a proxy indicator of transactions (defined as a wallet that has transferred more than $50 million at least once), it is not a verified identity or classification of current balance.
Why a single discovery is not enough as a trading signal
Wallet is not equal to a person. A wallet does not represent a trader, and participation share data cannot identify these groups as retail investors, market makers, or automated strategies. The paper does not establish profitability, causality or future price direction. The unconfirmed claim-that whale alerts allow holders to profitably follow orders-goes beyond what is supported by the evidence.
This is crucial for those interpreting whale narratives on the chain. When a dormant Bitcoin whale moves billions of dollars, people's instinctive response is to interpret its intentions; but this paper suggests that the observable footprint is a transient group response rather than a verified documentary transaction. Bitcoin was trading at $77,303 at the time and the Fear and Greed Index was 63 (in the "greedy" range), which provided broad market context rather than a reaction to the paper itself.
Research details needed to place findings in context
Event isolation design keeps samples tight. By excluding events in which there were no other whale transactions within 120 minutes, the study filtered out 6,645 Bitcoin and 5,075 Ethereum whale transactions, derived from whale alert notices covered from December 14, 2017 to December 31, 2025.
Definitions, Sample and Effect Size
The data set for directional regression runs is narrower than the isolated event count set. After removing observations with unclear directions, the buy and sell analysis used 5,884 Bitcoin events (including 3,471 buys and 2,413 sells) and 4,843 Ethereum events. This directional sample size is a missing detail from a competitor's report and defines the scope of what group statements can support.
Non-whale size groupings are also reallocated in fixed January-June and July-December periods based on the maximum transaction amount per wallet: small below the 50th percentile, medium between the 50th and 95th percentile, and large at or above the 95th percentile. The whale's state remains the same throughout the process. The medium-sized group showed the largest fluctuations, in part due to this percentile segmentation approach rather than evidence of individual behavior. The same caution applies to any single wallet event, from the group in this study to the fluctuations in ETF flows in the daily headlines.
Readers should also weigh the status of the document. WP26 -42 calls itself a preliminary study circulated for discussion, and its disclaimer states that the author's views do not necessarily reflect the views of the Philadelphia Fed or the Federal Reserve system. This is central bank research on the structure of the cryptocurrency market, not rules, enforcement actions or policies that have been adopted; no new investor obligations will arise from it.
Disclaimer : This article is for information purposes only and does not constitute financial or investment advice. There are significant risks in the cryptocurrency and digital asset markets. Be sure to conduct independent research before making a decision.