Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
 BTC
 ETH
The Financial Commission of Korea releases a roadmap for tokenized securities: three-phase legal and technical foundation
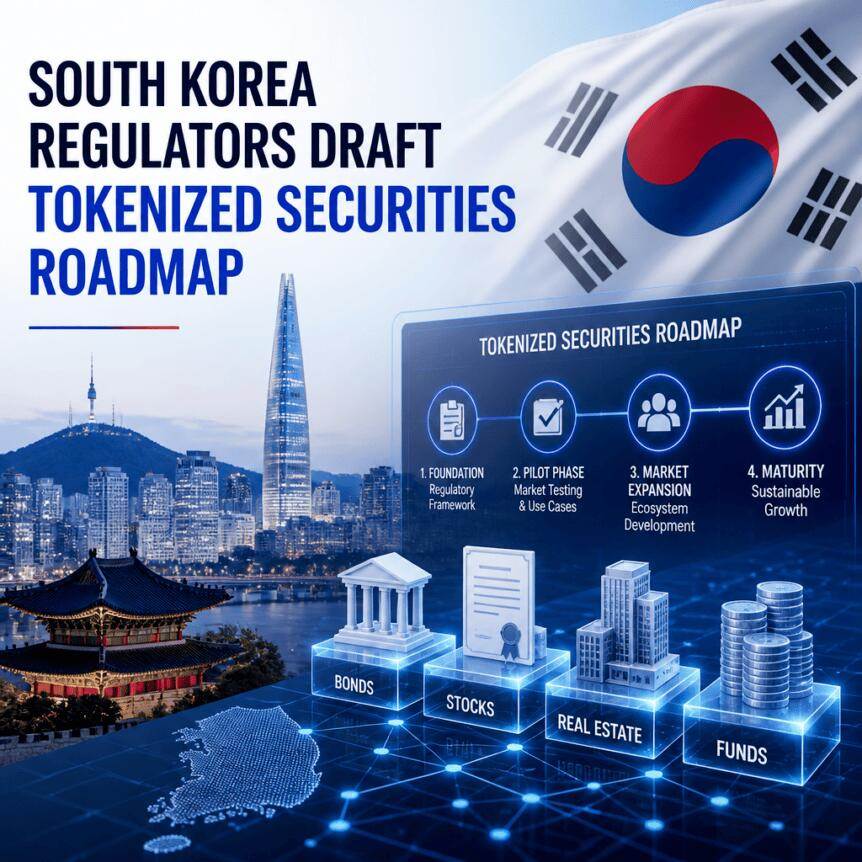
The Financial Commission of Korea (FSC) has developed a three-phase plan to establish a legal and technical foundation for issuing tokenized securities. If implemented as planned, the plan will clarify how on-chain securities will integrate into the country's existing capital market framework.
The FSC said in a press release issued on Friday that with the amendment of the Electronic Stock and Bond Registration Act, tokenized securities are expected to receive formal legal recognition starting on February 4, 2027. In addition, the initiative also points to a later stage, namely, the connection between tokenized issuance and stablecin payments.
Core Points
- Legal Recognition Time: The FSC plans to legally recognize tokenized securities from February 4, 2027 by amending the Electronic Stock and Bond Registration Law.
- Phase 1: covers the legal recognition of tokenized versions of selected instruments, including certain funds, bonds, unlisted stocks, and decimated investment securities.
- Phase 2: Expand tokenization to all publicly issued securities.
- Phase 3: Regarding the on-chain payment process related to stablecoins, it indicates that regulators regard stablecoins as part of the settlement system.
Before launching this roadmap, FSC intends to work with Korea Securities Depository Corporation (KSD) to develop the necessary tokenization infrastructure.
Legal recognition conversion with specific date
To date, tokenized securities have faced regulatory uncertainty in many jurisdictions-often involving issues such as legal status, transfer mechanisms and settlement. South Korea's plan attempts to eliminate at least one major point of friction by tying recognition of tokenized securities to specific legislative timetables.
FSC stated that starting from February 4, 2027, after the revised version of the Stock and Bond Electronic Registration Act takes effect, tokenized securities will be recognized as a digital form of securities. The move aims to align the form of tokenization with the legal infrastructure already used to electronically register and process stocks and bonds.
The roadmap is described as part of the implementation of the revised Capital Markets Law and Electronic Securities Law, which the FSC has positioned as the country's first tokenized securities framework.
Details of the three stages
The FSC's approach is phased, expanding from the recognition of specific tools to broader applications, and then moving to a more integrated on-chain settlement model.
The first phase focuses on bringing tokenized securities into regulatory and legal protection, but is limited to a specific set of products. According to the FSC, legal recognition will apply to tokenized securities that include the following:
- Institutional Money Market Funds
- Bonds
- Unlisted Equities
- Equalized Investment Securities
Phase 2 Extend tokenization to All publicly available securities 。For market participants, this sequencing is crucial: It suggests that issuers and intermediaries will first be required to adjust their operational and compliance processes for a controlled toolset, and the rulebook may then be expanded to cover a wider range of public offerings.
The third stage is the most ambitious and forward-looking. The FSC said its goal is to enable on-chain payments connected to stablecoins . Although the announcement did not elaborate on technical standards or regulatory restrictions for stablecoins in this context, the final stage included payments associated with stablecoins, indicating that regulators are considering not just token issuance, but also settlement and the process from custody to payment.
Regulatory steps and the role of market infrastructure
In addition to the legislative timetable, the FSC also outlines additional recent administrative work. It said it plans to propose amendments to relevant ancillary regulations by the end of September-a step that often determines how the law works in practice, including operating rules governing issuance, transfer and compliance.
Importantly, the FSC also stated that it would decide on the timetable for Phase 2 and Phase 3 after preparing ancillary amendments, which means that the later stages are not fully locked before the February 4, 2027 recognition date.
Prior to the launch of the roadmap, the FSC said it would work with Korea Securities Custody Corporation (KSD)Collaborate to develop the tokenized infrastructure required by the framework. This is critical for investors and companies, because successful tokenization depends largely on the readiness of the core market infrastructure-including interfaces with registries, confirmation of ownership records, and the ability to reconcile on-chain activities with existing capital market processes.
Why the roadmap shows a tightening of regulatory stance
The announcement comes as South Korean regulators are steadily moving closer to a clearly defined system for tokenized assets. According to previous reports on the FSC's position, the FSC has pointed out that it will announce detailed rules for tokenized securities in 2027 and incorporate them into the country's capital market framework.
In addition, South Korea has been experimenting with the concept of tokenized settlement outside of securities issuance. In April this year, the Ministry of Finance of South Korea announced a pilot project to use tokenized deposits to implement government operating expenditures, and plans to be fully rolled out in the fourth quarter of 2026. This work is independent of the FSC's tokenized securities framework, but it strengthens a broader regulatory direction: not just for transactions or issuance, but potentially for real-world payments and operational transfers.
Taken together, the FSC roadmap suggests that South Korea is trying to reconcile two often conflicting priorities in tokenization discussions: while retaining legal certainty in traditional capital markets, leaving room for blockchain-based representation and ultimately on-chain payment tracks.
At the same time, the phased nature of the plan left suspense about practical issues. The biggest uncertainty facing market participants may be how quickly the second and third phases will advance after drafting ancillary regulations, and what technical and compliance requirements will accompany on-chain payments associated with stablecoins.
For readers following this area, the next signal to watch is the FSC's response to ancillary regulatory revisions completed by the end of September, and the details that emerge in its coordination with KSD-particularly any information clarifying how settlements, custody records and payment flows associated with stablecoins are handled under the updated legal framework.