Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
 ARB
 BTC
 ETH
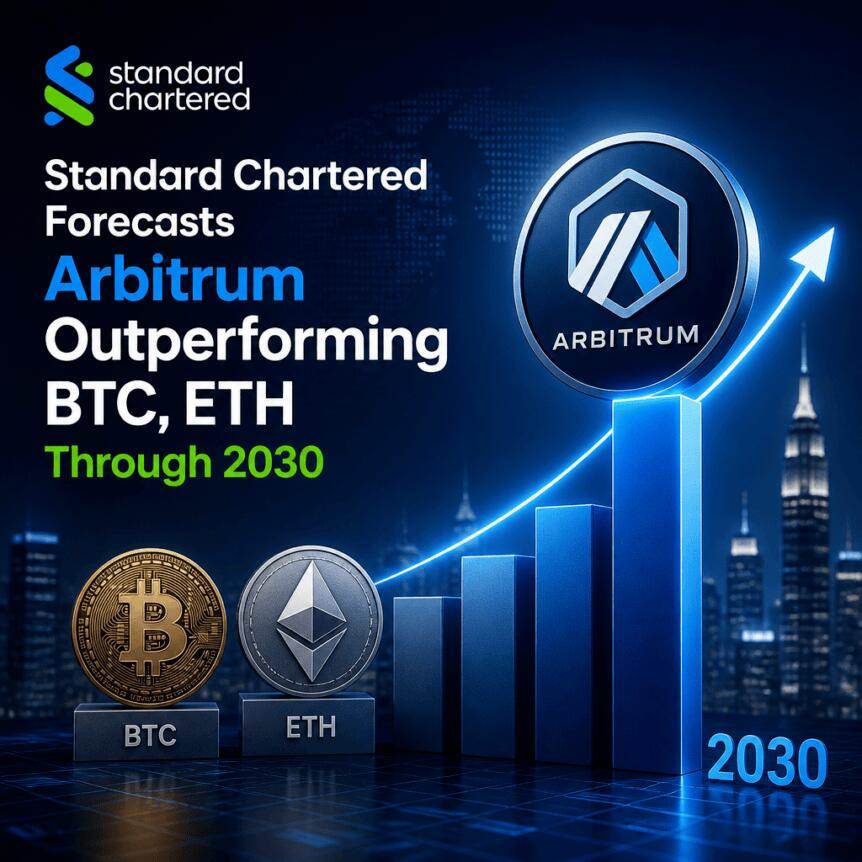
渣打银行:Arbitrum 有望在 2030 年前成为加密市场最强表现者
渣打银行(Standard Chartered)提出观点,认为 Arbitrum 有望在 2030 年之前成为加密货币市场中表现最强劲的资产之一。该行指出,随着传统金融领域链上活动的增加,该网络的收入机制可能从中受益。渣打银行全球数字资产研究主管 Geoff Kendrick 在与媒体分享的一份报告中指出,Arbitrum 的经济设计可能是超越原生加密用户增长的新动力来源。
Kendrick 表示,Arbitrum 能够获取在其网络上构建业务的企业所产生的净协议收入的 10%。他特别提到了 Robinhood Chain——一个与在线经纪商 Robinhood 关联的以太坊 Layer-2 倡议——作为早期案例,展示了以代币化为重点的应用程序如何改变 Arbitrum 的财务格局。据 Kendrick 称,这种影响已经体现在网络的收入运行率中。
核心要点
- 渣打银行预测,随着更多传统金融资产上链,Arbitrum 的协议收入份额可能会显著增长。
- Arbitrum 的设计使其能够从在其网络上构建业务的公司那里获得 10% 的净协议收入。
- 渣打银行认为 Robinhood Chain 实质性地改变了 Arbitrum 的经济模型,预计其九月收入将达到 500 万美元。
- Kendrick 预期这些经济因素将支撑 ARB 价格多年上涨,到 2030 年 potentially 达到 10 美元。
- 主要风险包括代币化采用速度放缓以及来自其他区块链的竞争加剧。
为何渣打银行认为 Arbitrum 的收入可以规模化
渣打银行看多 Arbitrum 的核心观点在于,其增长不仅仅关乎用户活动,更关乎网络在协议收入中的占比。Kendrick 描绘了这一路径:随着受监管机构和金融机构通过代币化真实世界资产(RWA)产品将更多资产引入区块链基础设施,支持这些部署的 Layer-2 网络有望捕获经常性价值。
Ronbinhood Chain 被用作这一动态的具体例证。在该报告中,Kendrick 认为其发布已经影响了 Arbitrum 的经济状况。他指出,按照当前的运行率,预计 Arbitrum 将在九月产生 500 万美元的收入,这比 Robinhood Chain 于七月推出之前的水平高出五倍多。
对于投资者和交易者而言,这一点至关重要,因为它将叙事从单纯的“Layer-2 使用量”转向了“Layer-2 货币化”。如果代币化资产工作流程能产生持续的协议收入,那么对该网络原生资产的代币激励和长期需求可能会随之受益。渣打银行的框架本质上是:代币的价值主张与商业采用和网络经济学挂钩,而不仅仅是零售活动。
From protocol economics to ARB price assumptions
Kendrick's views on prices, while aggressive, are rooted in the bank's revenue-oriented logic. He expects Arbitrum's economic conditions to support ARB's steady rise over the rest of the decade, predicting that the token will potentially reach $10 by 2030. The bank's forecast implies an increase of about 70 times from current levels.
Standard Chartered Bank also compared its outlook for Arbitrum with expectations for Bitcoin and Ether over the same period, saying ARB's expected returns will be much higher than the latter. Although price forecasts are inherently uncertain, the bank's presentation method is noteworthy: its arguments are based on the agreement's growing revenue streams rather than purely speculative momentum.
At the time of the report's release, ARB was valued at approximately US$0.14, an increase of 86% in the past month, according to CoinGecko.
Tokenizing real-world assets is the engine in the model
Standard Chartered's argument is deeply influenced by the trend of tokenization. Kendrick cited data from RWA.xyz to point out that the cumulative RWA tokenization scale has reached nearly US$39 billion. The bank reiterated its broader forecast that tokenized assets could reach $4 trillion by the end of 2028, as banks and asset managers put more assets on the chain.
In this scenario, Layer-2 networks like Arbitrum are considered infrastructure providers. The bank's logic is that as monetization moves from experimentation to larger-scale deployments, companies building businesses on these networks can generate net agreement revenue-some of which flow back to Arbitrum based on the 10% share model.
Standard Chartered Bank has previously linked a broader view of crypto to growth, including taking a bullish stance on Chainlink and the broader decentralized finance (DeFi) sector in the context of growth in the chain's asset base. This report on Arbitrum continues the same thread: As more "real-world" Expositions are released online, the infrastructure that supports distribution, settlement and related services may capture more lasting value.
Key uncertainties and competitive pressures
Despite his optimism, Kendrick also pointed to risks that could cause the bank's price framework to fail. He identified two main uncertainties: asset tokenization is slower than expected and increased competition from alternative blockchains .
This is an important tension that readers need to weigh. The potential upside for Arbitrum depends not only on technology and adoption milestones, but also on whether tokenized assets are concentrated within a specific L2 ecosystem or dispersed across multiple networks. If tokenization expands but is scattered among competing platforms, Arbitrum's share of revenue-which in turn dilutes the logic of pegging earnings to tokens on which Standard Chartered relies-could be weakened.
预测中还嵌入了时间要素。Kendrick 预测的收入运行率增长及由此产生的 ARB 前景,假设新的部署和货币化机制以可持续的方式逐步推进,从而维持协议收入。如果“资产发行增长”与“协议货币化”之间存在任何不匹配,很可能迫使该论点进行重新校准。
随着市场消化这份报告,接下来需要关注的是以太坊 Layer-2 上的代币化活动是否持续加速,以及 Robinhood Chain 或其他面向代币化的部署是否继续为 Arbitrum 转化为可衡量的净协议收入。代币化资产采用的速度和替代链之间竞争的激烈程度,可能会决定现实情况与渣打银行多年期模型的吻合程度。