Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
 BTC
 ETH
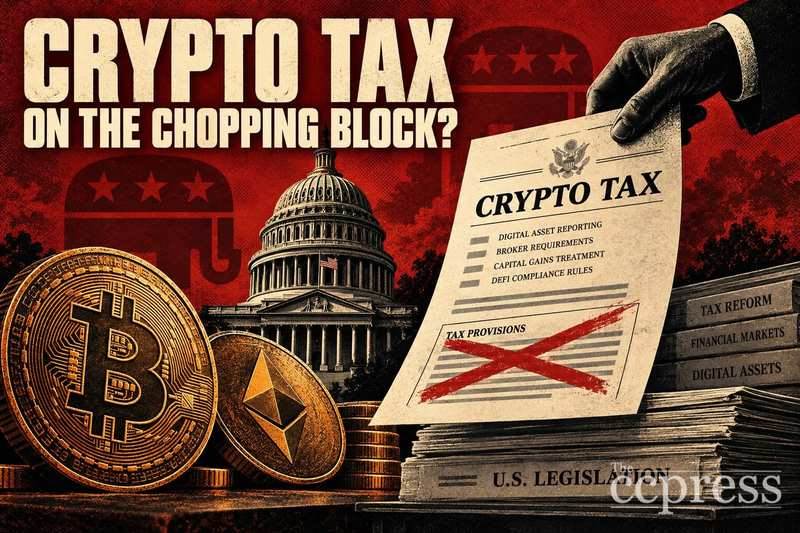
Republicans on the House Ways and Means Committee are considering removing tax provisions covering cryptocurrency mining and pledging from the broader digital assets bill
Republicans on the House Ways and Means Committee are reportedly weighing whether to remove tax provisions covering cryptocurrency mining and pledging from a broader package of digital assets bills. If the measure is retained in the final vote, it will reshape the way newly minted tokens are taxed.
Rumor considerations and current situation
The considerations in this report are related to the provisions on cryptocurrency mining and pledge. According to unconfirmed information, Chairman Jason Smith is exploring the possibility of removing the provisions in a bid to build Democratic support ahead of the midterm elections, but the committee has not issued an official statement confirming that such deliberations are under way.
It needs to be emphasized that this is only a possible removal proposal, not a final decision. Current records do not indicate that any terms have actually been deleted, revised or promulgated. There was a lack of major documentation behind the news reports, and only one source reported on the internal negotiations.
What are the cryptocurrency tax provisions on the table?
Unconfirmed reports did not clearly state the specific legal provisions being reviewed. But what can be verified is that the underlying proposal it seems to point to is: the Mining and Pledge Tax Clarity Act (H.R.) introduced by Rep. Mike Carey on June 8, 2026. 9175, Tax Clarity for Mining and Staking Act) and submitted to the Ways and Means Committee in accordance with the official text.
The bill's proposed section 1400W-1 stipulates that when newly minted digital assets are acquired, their fair value should be included in general gross income and that amount should be included in the tax basis. Its proposed section 1400W-2 provides an option: eligible newly minted assets are not considered income simply because they are acquired, but the required acquisition costs must be capitalized and cannot be deducted otherwise.
This trade-off is more profound than a simple postponement. Under the proposed section 1400W-2(b), gains on disposal of these assets will be recognized and treated as property gains on non-capital assets. Unless revoked with the consent of the Ministry of Finance, the election applies to the election year and subsequent years, with partnerships and S-type companies making choices at the entity level.
The proposed section 1400W-3 also treats certain trust allotments and transfers of the deceased's estate as disposals, so its application goes beyond mere cash sales. Section 2 applies the rules to assets acquired during the tax year beginning after the enactment; the text itself does not set an promulgation date and does not provide for modification procedures.
How the proposal conflicts with the current IRS position
Stakes are the clearest in the current legal context. IRS Revenue Ruling 2023-14 stipulates that taxpayers adopting a cash payment basis should include the fair value of pledge verification rewards into total income in the year in which they obtain control and control of the rewards.
The ruling fixes the fair value at the date and point in time when control is obtained, and extends the same treatment to rewards obtained through cryptocurrency exchanges. It also cited Notice 21 of 2014 (Notice 2014-21), which treats cryptocurrencies as property and stipulates that once taxpayers gain control and control of mining incentives, they should be counted into total revenue.
This bill on mining and pledge will open up an alternative path from default rules. This is why removing it is important and why it deserves close attention if the report is true.
Report what has been changed and what has not been changed
The word "consider" alone will not change current tax obligations. Any claim that the clause has been deleted needs to be confirmed through a verified committee statement or an updated legislative text, neither of which currently exists.
Broader legislative developments, including Senator McCormick's recent efforts to push for a vote on the CLARITY bill, show how quickly the language of cryptocurrency policy is changing. So, if mining and pledge rules are stripped before the modification phase, will the IRS's default rules continue to apply?
Disclaimer : This article is for reference only and does not constitute financial or investment advice. There are significant risks in the cryptocurrency and digital asset markets. Do your own research before making a decision.