Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
 USDG
Analysis of Aave's February USDG principal token rollover proposal: Implicit rate of return and risk variables
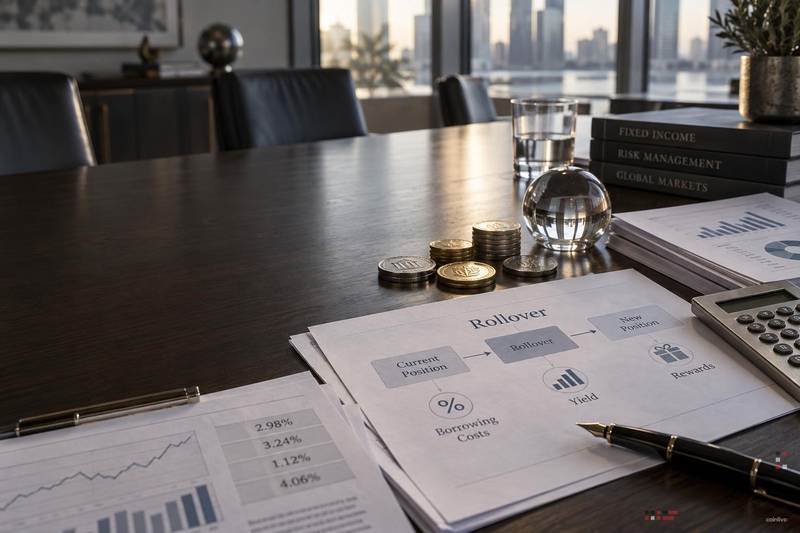
A governance proposal on rollover USDG (US dollar stablecoin) principal tokens in the Aave Agreement, its stated implied annualized rate of return is 2.98%. However, two key variables complicate this data: current borrowing costs are high and the reward portion attached to the position has not yet been recognized.
Core content of the proposal
This rollover is for USDG principal tokens, a fixed-term tool used in Aave's lending infrastructure. Principal tokens separate the principal and income portions of a deposit; through a rollover operation, positions can be extended to a new term rather than redeemed at maturity. According to relevant reports, the implied annualized rate of return reflected in the proposed rollover offer is 2.98%.
It needs to be clear that this figure represents an "implied rate of return" rather than a guaranteed return. It reflects the current market pricing of principal tokens rather than a locked fixed payment amount. This means that before and after implementation, the actual rate of return will fluctuate as market conditions change. Previously, Aave had adjusted earney-related parameters based on liquidity conditions, such as when the stablecoin pool dried up, Aave had increased the annual interest rate on its GHO borrowing to 4.5%.
Borrowing costs compress net income
Higher borrowing costs on Aave reduce the attractiveness of any head that needs to borrow money to fund or leverage rollover operations. If a participant enters or maintains a USDG principal token position by borrowing, then the spread between the 2.98% implied yield and the prevailing (current) borrowing rate will determine whether the transaction has a value-added effect. According to existing reports, the proposal does not quantify the current borrowing cost gap.
This sensitivity to cost is particularly important for participants using Looped Strategies. A similar situation occurred during the influx of large stablecoins into the agreement; when $149.6 million USDC was transferred to Aave, both utilization and borrowing rates in the affected pools changed.
Uncertain rewards leave final returns open
Rollover may come with additional rewards in addition to the underlying implied rate of return, but in the currently reported proposal, these rewards have not yet been confirmed. This distinction is crucial: the implied rate of return of 2.98% is a market-derived input, while reward allocation depends on governance decisions that may change or be cancelled before the February rollover date.
When evaluating the proposal, participants should focus on three outstanding matters by February: the final extension terms adopted by the governance body, the current borrowing rate at the time of implementation, and the formal confirmation or rejection of the incentive component. A similar principal token event on Aave-the Pendle AUSD principal token (worth $67.4 million) that expired on October 8-demonstrated how expiration mechanisms and rollover operations interact with real-time market conditions.
Summary of key points
- 2.98% implicit annualized rate of return: reflected in the February USDG principal token rollover proposal.
- Higher borrowing costs: Reduced net yield on leveraged or revolving strategy positions.
- Reward conditions not confirmed: Final return is subject to governance approval before implementation in February.