Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
 BTC
Regulatory developments in India and Europe: Two-way evolution of crypto-related market structures
At the launch of the pilot project, the Securities and Exchange Commission of India (SEBI)'s "Demat 2.0" pilot successfully transferred more than US$100 million in tokenized corporate bond trading volume through distributed ledger infrastructure. According to the current design of the pilot, private keys of tokenized bonds are not controlled by individual investors, but are held by depositors.
At the same time, the European Securities and Markets Authority (ESMA) reiterated that binary options rules also apply to event contract platforms and questioned the partial implementation of the EU geographical blockade on platforms such as Polymarket and Kalshi.
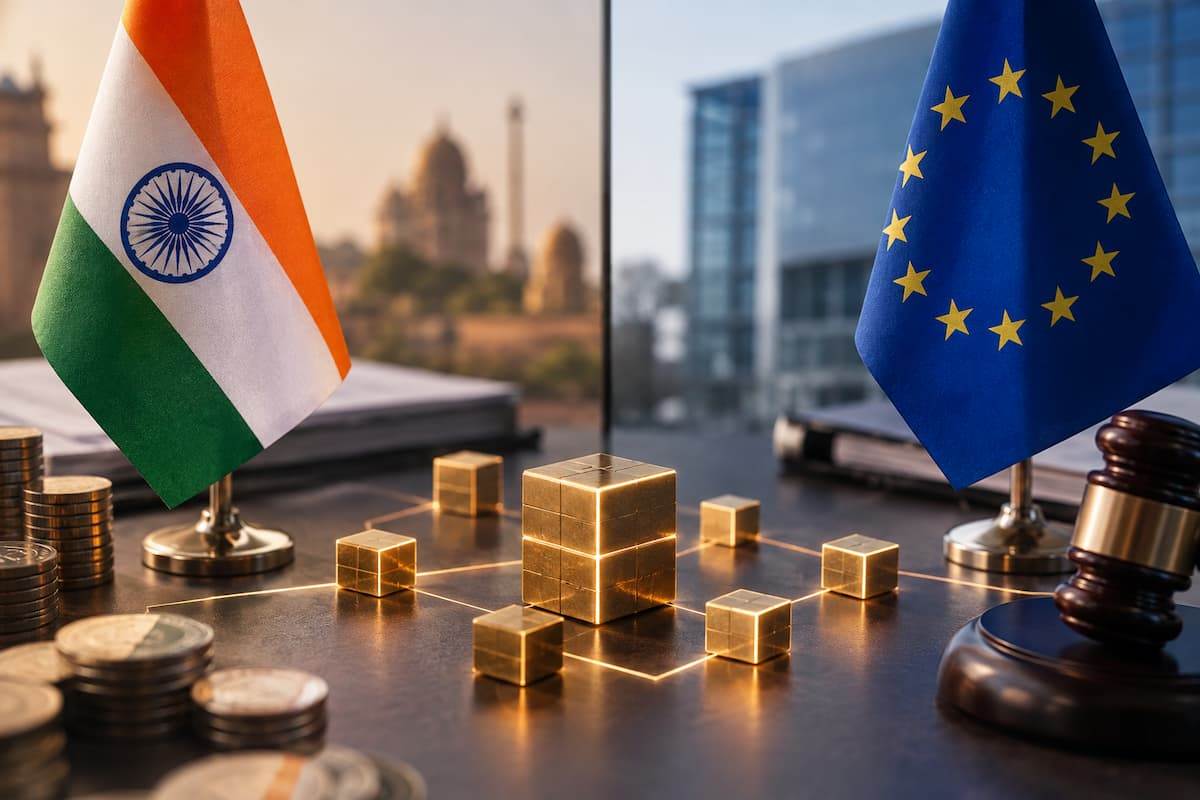
This week, two regulators on opposite sides of the world promoted the development of crypto-related market structures, but in very different directions.
India: Innovation in tokenized bonds under controlled pilots
The Securities and Exchange Commission of India (SEBI) has launched a pilot program to allow corporate bonds to exist in tokenized form on top of distributed ledger infrastructure. This move does not replace the existing paperless securities system, but runs in parallel with it. On the first day of the pilot launch, more than US$100 million in corporate bonds were circulated, a meaningful initial transaction volume for a project still in the testing phase.
Under the current design, the depository responsible for keeping India's paperless securities holds the private key that controls tokenized bonds, rather than individual investors. This is a deliberate structural choice: It retains custody within a layer of regulated intermediaries that investors and issuers already trust, rather than forcing retail participants to keep their own encryption keys. This kind of one-step transformation is something regulators in multiple markets are reluctant to try easily.
SEBI's official press release index is its main channel for issuing updates on pilot progress. The pilot is in line with the model SEBI has long built: introducing distributed ledger technology to India's securities infrastructure through controlled, well-defined pilots, rather than adopting comprehensive market mandatory orders. If the pilot is successful, tokenized settlement is expected to shorten settlement cycles and reduce reconciliation costs in the Indian corporate bond market. Given that bond settlement has historically been slower and more cumbersome than stocks, Indian regulators have pointed to the urgent need for modernization in this area.
Europe: Strong regulatory stance on forecasting platforms
In Europe, the European Securities and Markets Authority (ESMA) has taken a more confrontational stance towards forecasting platforms, another corner of the market. ESMA reiterated that event contract platforms fall under the jurisdiction of the EU's existing intervention measures on binary options products, which were originally intended to limit retail investors 'access to high-risk derivatives products.
ESMA specifically named Polymarket and Kalshi in its statement, questioning whether the limited geographical blockade imposed by various platforms on EU users is sufficient to exempt them from EU authorization requirements, or whether EU residents can still access these markets through circumvention, making the geographical blockade a mere formality.
This distinction highlighted by ESMA is crucial to how the rest of the industry interprets regulatory signals. If a platform blocks EU IP addresses but still allows EU residents to fund accounts in other ways, or only geo-blocks certain product types to make other products accessible, this may not meet regulatory requirements that focus on substance rather than form.
Over the past year, the market has been forecast to grow rapidly and has evolved from a niche cryptocurrency product to something that regulators in multiple jurisdictions regard as a separate asset class, requiring a dedicated system of rules rather than default inclusion in existing cryptocurrency or gambling frameworks.
Conclusion
Together, these two initiatives capture the true state of current crypto-related regulation: not in a single global direction, but in two distinct regulatory postures operating in parallel. One side opens up controlled channels for tokenization of traditional assets, while the other side tightens borders and strengthens controls on fast-growing products that cause regulators to worry that they have exceeded the scope of established rules.