Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
French 10-year bond yields exceeded 4.3%, hitting a new high since 2008.
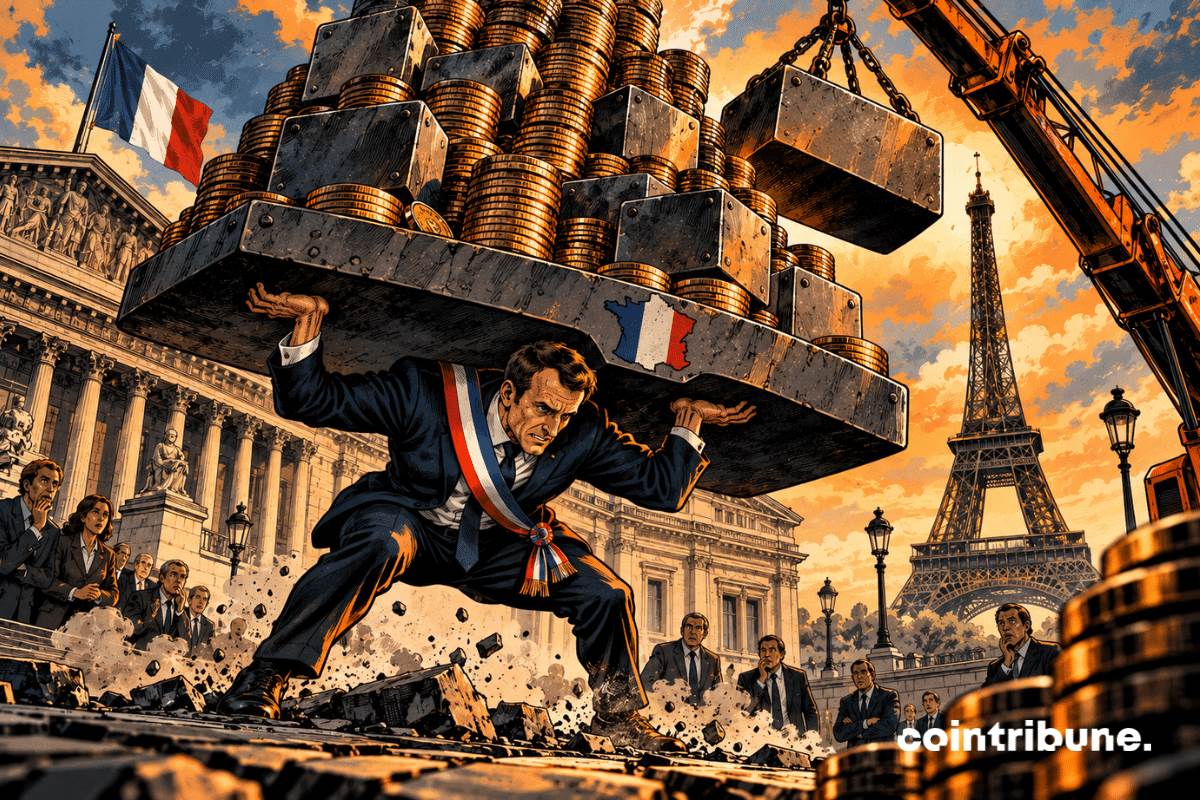
French 10-year bond yields have climbed to more than 4.3%, reaching unprecedented levels since the 2008 financial crisis. However, this increase in interest rates will not immediately reassess all countries 'debt, but will gradually increase their refinancing costs.
Core Points
- French 10-year bond yields exceeded 4.3%, setting a peak since 2008.
- Newly issued debt and refinancing debt as matures have gradually increased the country's borrowing costs.
- The France-German spread is close to 90 basis points, indicating an increase in risk premiums.
- The rise in yields also affected the international bond market.
- Long-term high interest rates may compress France's fiscal space.
The cost of new debt rises
On September 9, the yield on French 10-year government bonds (OAT) was about 4.3069%, leading to a sharp increase in debt interest expenses. OAT is a bond issued by the French government to finance public expenditures and repay maturing securities. Its yield is equivalent to the compensation return required by investors.
In June last year, the rate was still around 3.6%; it rose to 3.90% a month ago. According to statistics, at the auction in early September, Agence France Trésor had to offer a yield of 4.23%, compared with 3.90% in August and 3.73% in July.
Several indicators reflect current market tensions:
- French 10-year OAT yield rose 8.5 basis points to 4.3069%;
- French 30-year bond yields exceeded 5%, reaching 5.04%;
- German 10-year bond (Bund) yields were 3.4183%;
- France-German spreads were close to 90 basis points.
One basis point represents 0.01 percentage point. Therefore, this 90 basis point spread means that France needs to provide an additional yield of about 0.9 percentage points more than Germany. This difference reflects the risk premium investors demand.
It should be noted that the 4.3% interest rate does not apply to old bonds issued at a fixed interest rate in the early period. Countries will be affected only when they issue new bonds or replace maturing bonds. If high yields persist, the debt burden will gradually increase.
Bond markets under global pressure
The rise in interest rates is not caused solely by French factors. In fact, bond markets in Germany, the United States and the United Kingdom are also facing difficult times. If investors sell these securities, their prices fall and yields rise mechanically.
Rising oil prices have exacerbated fears of renewed inflation and pushed up transportation and production costs. In this context, central banks may maintain higher interest rates or even raise interest rates further. At the same time, countries and companies are issuing large amounts of debt, and oversupply forces borrowers to provide more attractive returns to attract buyers. As a result, German 10-year bond yields have reached their highest level since 2011.
It can be seen that France is influenced by international trends. However, its interest rate spread with Germany suggests that investors 'reactions are not based solely on the global environment, and they are also demanding additional risk premiums based on France's fiscal and political situation.
Debt burden compresses fiscal space
The French government has lowered its economic growth forecast this year to 0.5% from 0.7% and admitted it will not be able to reduce the public deficit to 5% of GDP as planned.
The debt burden is expected to reach approximately 65 billion euros in 2026, 4.5 billion euros higher than the original forecast, making it the country's largest expenditure item. If interest rates continue to rise, resources available for education, defense, medical care or energy transformation will be further reduced.
Kevin Thozet, a member of the Carmignac Investment Committee, said: "France is particularly sensitive to rising interest rates." He estimates that reducing the deficit ratio to 3% of GDP by 2029 may require an adjustment of nearly € 85 billion more than the current trajectory.
This estimate does not imply an immediate saving of € 85 billion, but rather assesses the gap between current public finances and the path needed to achieve European goals.
At present, France is still able to successfully find bond buyers and has not faced financing difficulties. The real risk lies in the rising costs every time the debt is renewed. Future fiscal choices must convey confidence to investors to prevent risk premiums from rising again.