Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
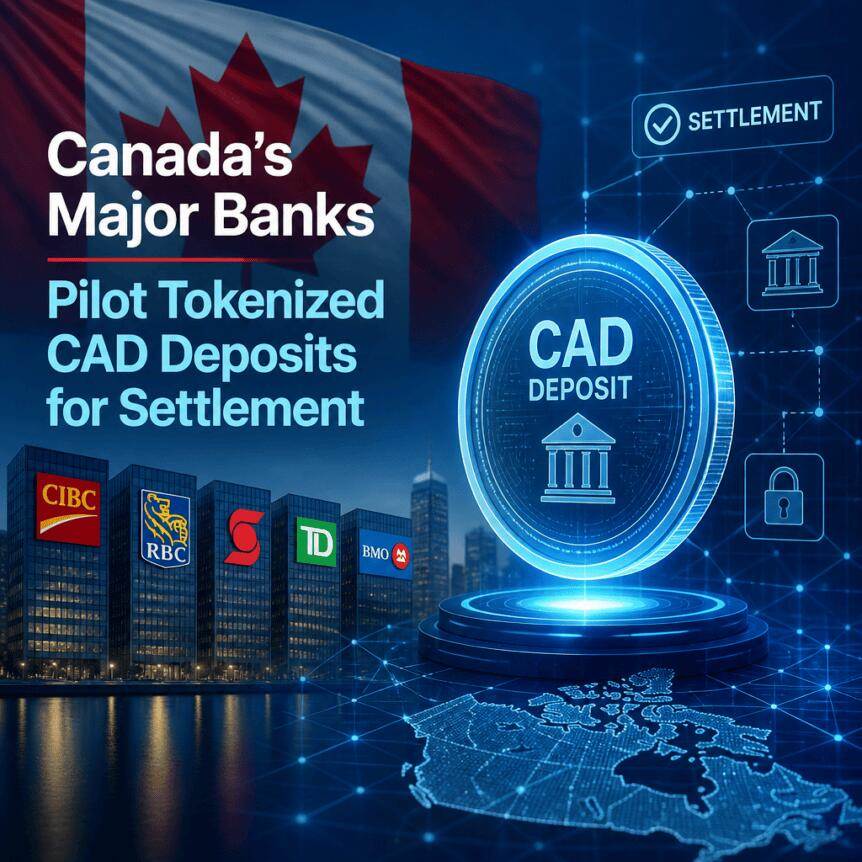
加拿大六大银行联手开发代币化存款转账新系统
加拿大的六大主要银行联合组建了一个联盟,共同开发一套新系统,旨在实现跨金融机构的代币化加元存款转移。此举旨在引入银行存款的数字版本,使其能够在国内各银行之间高效且安全地流转。
主要机构合作推进数字存款计划
该联盟成员包括蒙特利尔银行(BMO)、加拿大帝国商业银行(CIBC)、加拿大国家银行、加拿大皇家银行(RBC)、丰业银行(Scotiabank)以及多伦多道明银行集团(TD Bank Group)。这些银行于周二联合宣布了这一倡议,并概述了分阶段实施的计划。初始阶段将专注于促进加拿大银行系统内部代币化存款的转移,未来可能会将该平台与其他数字资产网络连接起来。
此次合作紧随加拿大首席银行监管机构最近的一项监管更新之后,为此类创新扫清了道路。不到两周前,加拿大金融监管机构办公室(OSFI)澄清了代币化存款的法律地位,指出代币化的存款代表与传统银行存款在法律上没有区别。OSFI 强调,存款背后的技术不会改变其法律性质。
OSFI 表示,代币化存款继续代表受监管银行的负债,其数字化形式并不改变客户与银行之间的基本关系。
It should be noted that tokenized deposits are completely different from stablecoins backed by legal currencies. Stable coins are usually issued by private companies and backed by reserve funds. Although tokenized deposits remain on the balance sheet of the issuing bank and enjoy deposit insurance protection, stablecoins are classified into different asset classes and may not enjoy the same protection.
Canada's new platform is designed to support faster, programmable payments and plans to integrate more deposit-based financial institutions in the future. Banks said developing secure and interoperable tokenized payment solutions is expected to bring broader innovation to the country's growing digital currency ecosystem.
Digital asset regulatory framework further expands
The advancement of the tokenized deposit project comes at a time when Canada is making significant progress in regulating digital currencies. In March this year, lawmakers passed the stablecoin Act (as part of Bill C-15), which aims to establish a federal regulatory framework specifically for fiat currencies supporting stablecoins. Under these rules, non-bank stablecoin issuers must register with a bank of Canada and fully support their tokens with high-quality liquid assets in a 1:1 ratio, while guaranteeing redemption at face value.
The regulatory framework for stablecoins is expected to take effect in 2027. However, these rules apply only to issuers that are not yet subject to existing prudential regulations-such as chartered banks and credit unions. Under the established methodology, only issuers of non-financial institutions fall under the jurisdiction of the law, and such tokens cannot be advertised as bank deposits or protected by a public deposit insurance scheme.
The new framework requires stablecoin issuers to hold sufficient reserves and limits the use of deposit-related terms on these digital assets.
Industry participants expect coordinated actions by Canada's largest bank, coupled with strict regulatory oversight, to help set the standard for global adoption of digital deposit and payment solutions. As banks enter the first phase and seek to incorporate broader applications into a changing landscape, this ongoing development process will be closely watched.
Tokenized deposits (bank-issued) vs. fiat supported stablecoins (non-financial institutions issued)
- Issuer: Regulated banks/non-bank organizations
- Classification and insurance: Considered as traditional deposits, insured/not classified as deposits, uninsured
- Regulatory basis: OSFI-regulated/Regulated by the Stabiloin Act (starting from 2027)
- Asset-liability attributes: Retained as bank liabilities/backed by 1:1 liquidity