Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
 BTC
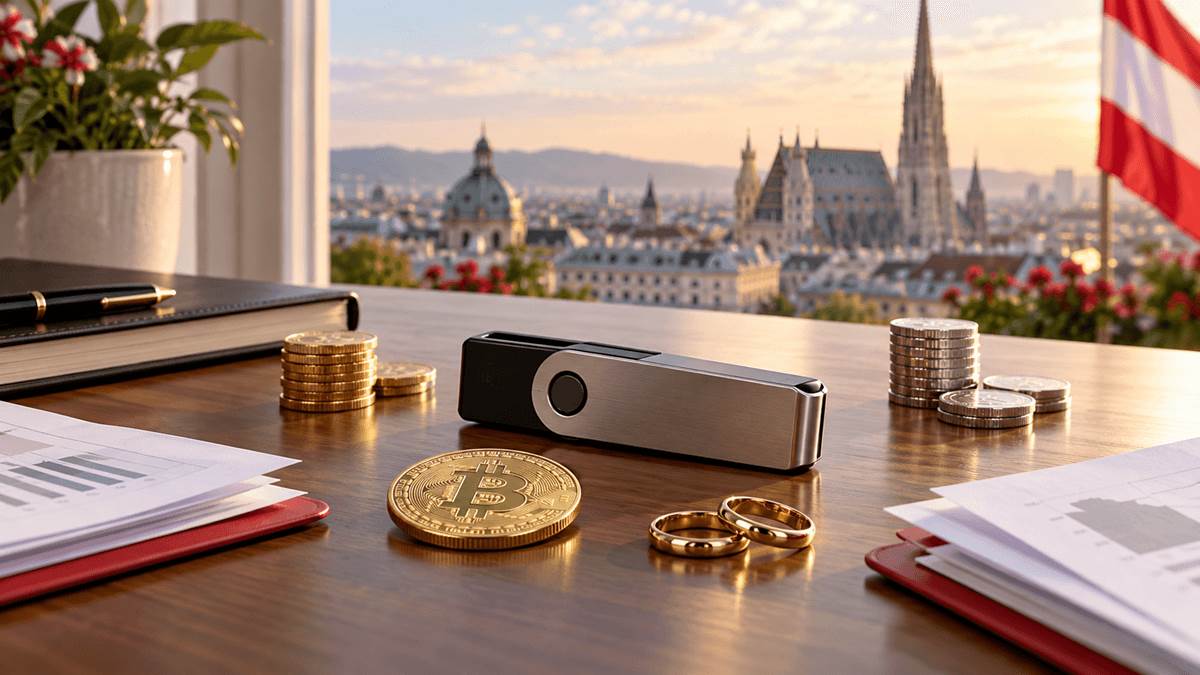
Transferring Bitcoin into the husband and wife's joint wallet: How to determine tax ownership?
A married couple jointly manages bitcoins in their hardware wallets. Both parties know the mnemonic and can initiate transactions. Does this mean that each party automatically owns 50% ownership of Bitcoin?
From a tax perspective, the answer is not that simple.
In Austria, the ownership of assets depends in principle on "beneficial ownership" and the overall picture of the actual situation. Technical access alone does not determine tax attribution.
Technology access does not equal equal ownership
The fact that both spouses know the mnemonic or private key does not in itself prove that ownership is equally divided for tax purposes. The following factors may have an impact:
- Who purchased Bitcoin;
- Whose assets funded the purchase;
- Who has the right to decide on the sale;
- Who economically benefits from gains and losses or bears losses;
- Whether there is an agreement between husband and wife.
The Austrian Administrative Court emphasized in particular that beneficial ownership is closely linked to the ability to actually dispose of assets and to exclude interference on a long-term basis.
Transfer your own bitcoins to a shared wallet
Suppose spouse A holds one bitcoin for many years and transfers it to a new hardware wallet whose mnemonic will be known to spouse B in the future. This simple technical transfer does not necessarily constitute a gift.
If A remains the sole beneficial owner and B only obtains technical access for management or backup, tax attribution may still be attributed to A.
The situation is different if half of the share is actually transferred
On the contrary, if B actually wants to obtain half of the bitcoins and freely dispose of that share in the future, it may constitute an asset transfer in the economic sense. At this time, it is necessary to review whether a donation of 0.5 bitcoins occurred.
In the case of gifts between spouses, Austria's gift reporting obligations may apply once the legal value threshold is exceeded.
Maintain clear separation of tax history
Using a common wallet can create complications when each spouse holds bitcoins with different acquisition costs. For example:
- A contributes 0.5 bitcoins, and the acquisition cost is 5,000 euros;
- B contributes 0.5 bitcoins, and the acquisition cost is 20,000 euros.
Technically consolidating them into one wallet should not cause different tax histories to become untraceable. In future sales, the acquisition date and cost basis may become determining factors.
Why personal records are important
It is recommended to keep the following records properly:
- respective original wallet addresses;
- Owner of each position;
- Date of purchase;
- Acquisition cost;
- Consolidation Date;
- Internal ownership agreement;
- 后续的出售和提款记录。
切勿将共同硬件钱包与共同银行账户混淆。
结论
位于夫妻共同钱包中的比特币,在税务目的上并不自动归夫妻双方平等所有。关键在于“受益所有权”:谁能够实际处置比特币,以及持有期间的机会和风险在经济上归属于谁?如果转移的目的是有意将所有权转让给另一方配偶,则可能额外涉及赠与行为。
(截至2026年10月1日。本文不构成投资建议。价格和费用结构会发生变化;购买前请与提供商核实条款。)