Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
 BTC
Daily Morning Express
Today's top news:
Strategy CEO says: Selling at the bottom is the right decision
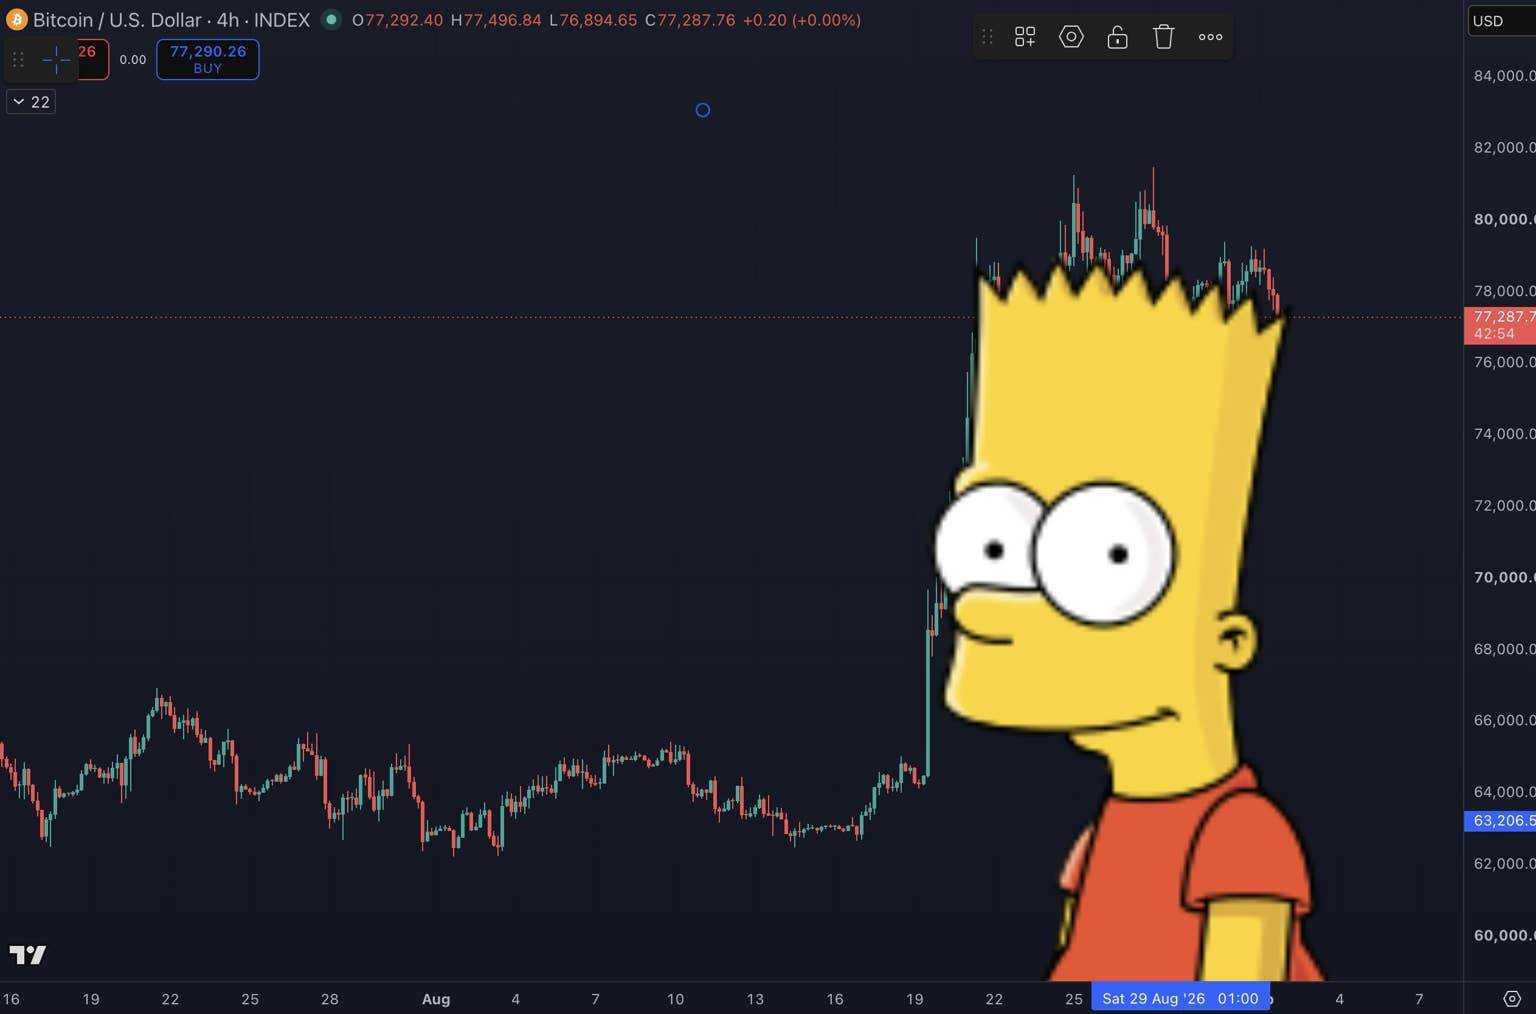
From late June to mid-August, Strategy sold a total of 6,916 bitcoins in four batches, with a weighted average selling price of approximately US$62,200. Last week, the company bought back 4,603 bitcoins at an average price of $80,318 each. Strategy CEO Phong Le pointed out in an interview with Bloomberg Crypto on Wednesday that both actions were the right decisions.
His core argument is that Bitcoin's price is not the only consideration in the decision. Previously, the company sold Bitcoin to raise funds to pay dividends on STRC (a preferred stock) when equity issuance was costly; now it is buying again because MSTR's stock has once again experienced a premium. During the two-month suspension, the company's assets grew to $72 billion, built approximately $7 billion in dollar reserves, and reduced net debt from approximately $7 billion to zero. A stronger balance sheet makes it cheaper to issue shares, making it more feasible to use these funds to buy Bitcoin.
Le also downplayed the scale and impact of the incident. He pointed out that the shares sold this time accounted for less than 1% of his holdings, and that the company's Bitcoin holdings have increased by 25% to 30% this year and currently holds 845,050 bitcoins worth approximately US$65.4 billion. He further emphasized that a "one-way accumulator" does not constitute a complete operating company, and that managing capital by buying and selling bitcoins, stocks and preferred shares is the company's core operating model. He defines Strategy as a two-way capital management company.
The key mechanism here is STRC, a variable-rate preferred stock that Strategy adjusts to keep its face value near $100. When the preferred stock price fell below par value in June this year, financing channels were blocked, and Bitcoin became their only way to try to restore parity, which has not yet been restored. Le is right, this is essentially a financing decision. But what he describes is a company whose bitcoin purchases rely on stock premiums, which in turn rely on bitcoin performance. This is a "three-body problem" that is difficult to balance, and they obviously chose to let MSTR equity holders take the most unfavorable situation. But in a bull market environment, these measures may yield generous rewards. We will see the results soon...