Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
 BTC
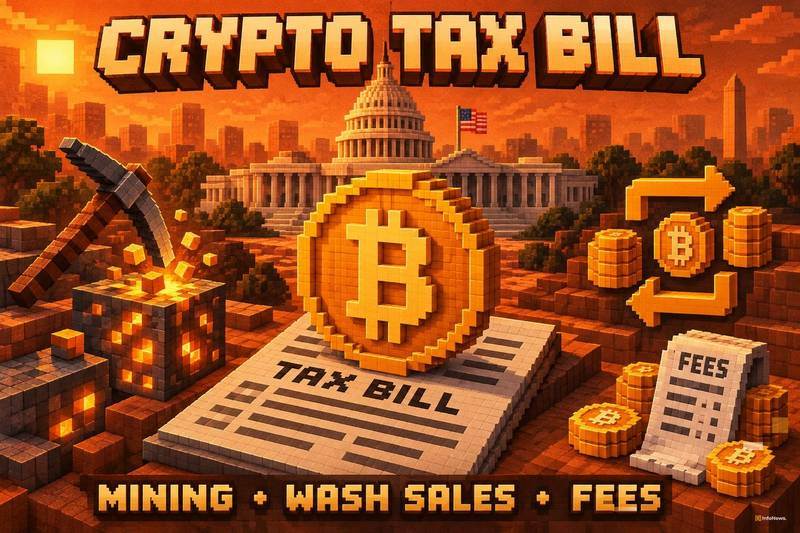
众议院筹款委员会发布加密资产税法法案:涵盖挖矿、洗售规则及网络手续费
众议院筹款委员会(House Ways and Means Committee)已发布编号为 H.R. 10357 的《数字资产税收确定性法案》(Digital Asset Tax Certainty Act)。该法案长达 114 页,内容涵盖比特币挖矿与质押、洗售交易(Wash Sales)以及网络交易手续费等关键议题。在正式表决之前,委员会计划于2026年9月16日星期三上午10点(东部时间)在 HVC-210 会议室举行全体会议审议(Markup),以对该法案进行修订和推进。
该法案由委员会主席杰森·史密斯(Jason Smith)于2026年9月14日提出,并移交至筹款委员会处理。目前这仅是一项提案,尚未成为生效法律;其条款仅在通过参众两院并由总统签署后才具有法律效力。对于比特币持有者而言,该法案的重要性主要体现在其对挖矿活动、工作量证明(PoW)奖励以及链上小额转账费用的规定上。这些规定触及了比特币生产和传输的网络基础机制,因此委员会对税务性质认定和时间安排的界定,其影响力超越了单纯的税法范畴。
挖矿活动的税务处理
Mining was one of the three major topics listed by the committee when it issued the bill, and the fourth title of the bill specifically deals with the tax treatment of verification activities. Section 401 stipulates that income supporting digital asset verification activities (including Bitcoin mining and pledge rewards) will be considered ordinary income. Its place of origin is usually determined based on the recipient's place of residence, except for branches. According to the draft text, this rule on the nature and source of tax applies to the tax year beginning after the bill is enacted. The committee's approach links tax results to where the miners or pledgers live, rather than where the underlying network operates.
In addition, section 402 aims to protect the classification status of trusts, so that even if specific pledge powers exist, certain pledge arrangements will not lose their trust status. However, the clause excludes any entity actively engaged in the verification business of digital asset transactions, which means that operating mining or verification companies cannot enjoy this exemption. This is consistent with the committee's overall effort to distinguish passive holders from professional operators, an idea that runs throughout the bill.
Laundering rules and transaction fees
Extension of Laundering rules
Section 301 extends the laundering rules in Section 1091 of the Internal Revenue Code to tradable digital assets. The change aims to end the current widespread practice of "immediately buying back the same currency after harvesting losses." This clause generally excludes eligible U.S. dollar stablecoins (subject to non-U.S. dollar functional currency exceptions) and does not include acquisitions related to transaction verification or periodic acquisitions recorded as ordinary income in the wash-out acquisition test.
The Joint Taxation Committee (JCT) stated in a one-page note issued on September 15, 2026 that the Chairman's alternative would adjust the effective date of Section 301 to disposal actions after September 14, 2026. This is a proposed effective date conditional on passage of the bill and does not mean that the rule has already applied. There is also a transitional provision that allows brokers to determine the adjusted base cost of customers for eligible disposals without applying Section 1091 until January 1, 2028, but this does not delay the effective date of the substantial washout.
Maximum exemption for network handling fees
In terms of handling fees, Article 101 proposes that when digital assets pay eligible network or transaction fees, no gain or loss will be recognized, provided that the total amount involved in the relevant verification or underlying transfer does not exceed US$10. This is a fee exemption and not a comprehensive tax exemption for retail cryptocurrency purchases.
For non-network transaction fees, the type of asset used to pay the fees must be the same as the type of asset disposed of or obtained in the underlying transfer. For example, there will be no exemption for fees paid to Bitcoin users using different tokens. This nuance constitutes a core qualification requirement for the Commission's microfinance relief measure. Broking, trading, liquidity and other related fees are also covered if conditions are met.
However, this fee exemption is not universally applicable. It generally excludes traders, brokers, dealers, verification bulk business operators, and individuals who have made more than 5,000 transfers of digital assets in the previous year (transfers used to pay fees are not counted in this threshold). The Ministry of Finance's administrative convenience relief and accounting method exclusions also apply. If the bill is passed, the fee exemption will apply to asset disposals after December 31, 2027, the latest phased launch date in the bill.
The bill has yet to be clarified
Although the committee has announced the meeting schedule, it should be noted that "plenary review" is the work part of amending and advancing the bill, and is not final adoption. The promulgation and review of a bill does not in itself establish the entry into force of the law. Many operational details exist in the chairman's alternative rather than in the original draft text, and the JCT's description only covers some of the changes (such as the washout effective date). Before the final approval text is determined, the specific interaction of the alternative with the original terms and any amendments that may be adopted during the review process need to be verified.
拟议的生效日期均附条件于法案的最终通过:手续费救济适用于2027年12月31日之后;洗售规则适用于2026年9月14日之后;而独立的经纪商报告过渡期则在2028年1月1日之前。除非法案成为法律,否则这些日期不会对纳税人产生约束力。
在市场表现方面,比特币在近期市场快照中交易价格约为75,614美元,24小时内下跌3.4%。这一波动反映的是宏观市场环境,而非对该法案的直接反应。最终,分配给挖矿和质押奖励的税务性质将对验证活动的经济模型产生更深远的影响,因为它直接决定了保障网络安全性的哈希率的税后回报,以及维持区块生产接近十分钟目标的难度调整机制。
免责声明:本文仅供参考,不构成财务或投资建议。加密货币和数字资产市场存在重大风险。在做出决策前,请务必进行独立研究。