Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
Recently, most of the holders of MSTR (Strategy) have been experiencing restless sleep. This once-prestigious asset, often referred to as the “Central Bank of Bitcoin,” is currently going through one of the most difficult adjustments since its listing. The price of Bitcoin plummeted from its high of $120,000, triggering a chain reaction. MSTR’s stock price was halved in just a short time, with a total decline of over 60%. The rate of value loss was comparable to that of a roller coaster descent. What’s worse, as volatility increases and its weight in the market decreases, MSTR even faces the risk of being excluded from the MSCI index. From being a mythical asset to undergoing a severe correction, MSTR’s fate serves as a reminder to the market: when you tie a company’s valuation closely to the price of Bitcoin, any increase will come quickly, but any decline will be even faster. The price adjustment and the halving of stock prices are merely superficial phenomena. What truly worries Wall Street is the increasing evidence that MSTR is involved in a battle for monetary power. This isn’t an exaggeration. Over the past few months, many seemingly unrelated events have begun to connect together: JPMorgan has been accused of disproportionately increasing their short-selling efforts against MSTR; there have been delays in the delivery of MSTR shares transferred from JPMorgan to other users; the derivatives market has frequently taken actions to suppress Bitcoin prices; discussions regarding “Treasury stablecoins” and “Bitcoin reserve models” have gained momentum at the policy level. And these aren’t isolated incidents. MSTR stands at the crossroads between two American monetary systems. On one side, there’s the old system: the Federal Reserve, Wall Street, and commercial banks (with JPMorgan as the core).
On the other side lies the new system that is being formed: a system involving the Treasury Department, a stablecoin framework, and a financial system based on Bitcoin as long-term collateral.
In this structural conflict, Bitcoin isn’t the target—it’s merely a battlefield for power struggles within the system. MSTR, however, serves as a key link in this conflict: it transforms traditional dollar-based institutions and debt structures into Bitcoin-based structures.
If the new system is established, MSTR becomes the central hub for transferring resources; if the old system remains stable, MSTR becomes a node that must be suppressed.
Therefore, MSTR’s recent decline isn’t simply an asset price fluctuation. There are three forces at work behind this: natural adjustments in Bitcoin prices; the vulnerability of MSTR’s own risk structure; and the external effects of power shifts within the dollar system.
Bitcoin has strengthened the Treasury Department’s future monetary framework, while weakening the Federal Reserve’s structure. The government faces difficult choices: if they want to maintain opportunities for low-cost accumulation, they need JPM to continue suppressing Bitcoin.
So, the methods used to target MSTR are well-organized. JPMorgan knows these rules perfectly well, because those rules were set by them. They have dissected MSTR thoroughly, identifying its veins (fund flows), bones (debt structure), and “soul” (market beliefs).
We’ve identified four possible “death scenarios” that MSTR might face. These are essentially the four fatal arrows prepared by the old order against MSTR.
Scenario one: taking advantage of the chaos to gain control.
This is the most straightforward scenario, and it’s also the one that gets the most discussion in the market. If BTC continues to plummet, with MSTR using leverage to amplify losses, resulting in a loss of ability to refinance assets, it could lead to a chain reaction of collapses.
This logic is simple, but it’s not the most important issue.
Everyone knows that “if BTC falls too much, MSTR will face problems,” but few people realize just how much lower the price needs to go for MSTR to become unstable.
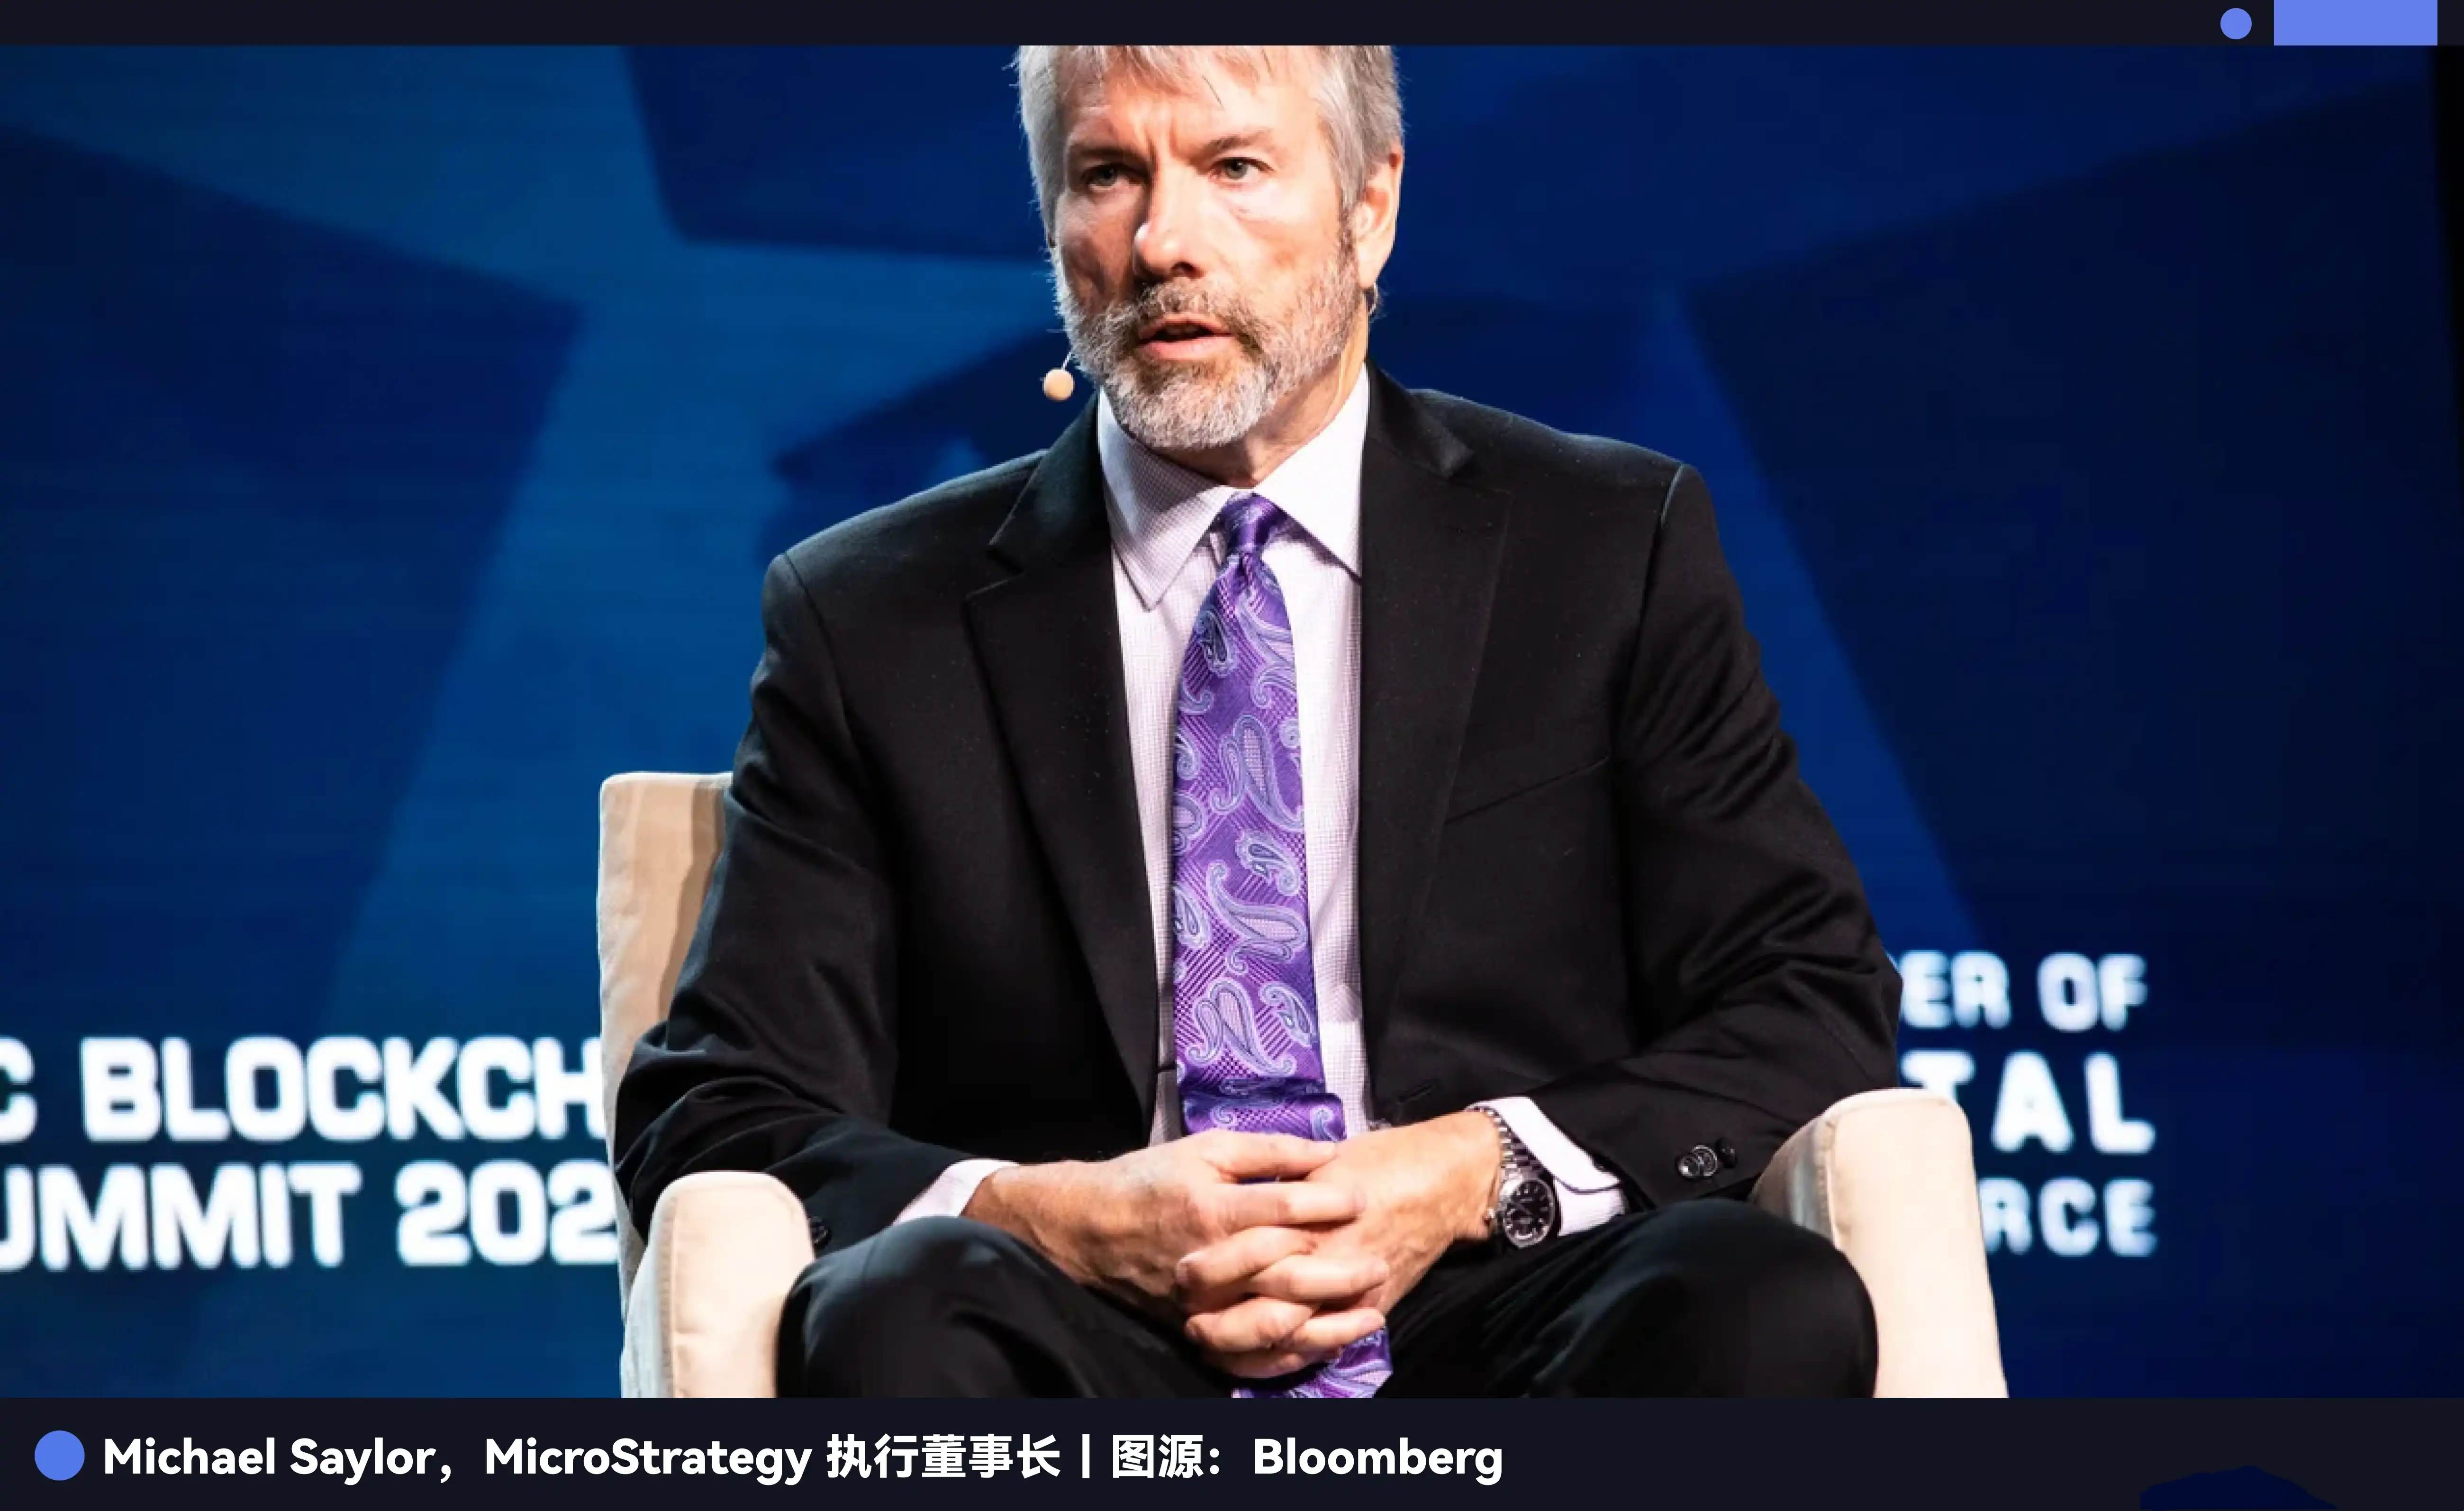
MSTR’s asset structure involves three key figures:
● Total BTC holdings exceed 650,000 units (about 3% of the total amount of Bitcoin).
● Average cost per unit is approximately $74,400.
● Some of the debts involve price risks (although they don’t result in forced liquidation, they still affect net assets).
Many stories about “MSTR being forced to zero” assume that it involves forced liquidation like in exchange contract situations. But in reality, MSTR doesn’t experience forced liquidation, but rather a “narrative-based forced liquidation.”
What does this mean?
Even if creditors don’t cause him to go into debt distress, the market can still cause his stock price to fall. When the stock price drops to a certain level, he won’t be able to issue more bonds or convertible bonds to cover his losses.
JPMorgan Chase and its allies are using the U.S. stock option market to short MSTR. Their strategy is simple: taking advantage of Bitcoin’s pullback to aggressively drive down MSTR’s value, thereby creating panic. Their goal is clear: to break Michael Saylor’s myth.
This is MSTR’s first “crackdown” point: the price of Bitcoin dropped so low that investors are no longer willing to pay him anything.
Second approach: forcing debts to be settled directly.
Before discussing convertible bonds, we need to understand how MSTR’s CEO, Michael Saylor, achieves his “magic.”
Many beginners think that MSTR simply uses the money he makes to buy more coins. That’s incorrect. MSTR engages in a very risky “leveraged arbitrage game.”
Saylor’s main strategy is to issue convertible notes, borrow dollars, and then buy Bitcoin.
This year, MSTR has raised a staggering $20 billion in capital, a figure that’s extremely rare among American listed companies. The sources of this capital include $11.9 billion from ordinary shares, $6.9 billion from preferred shares, and $2 billion from convertible bonds.
It may sound ordinary, but the real trick lies in the details.
These bonds offer investors extremely low interest rates (some even less than 1%), so why would investors buy them? Because these bonds include a “call option.” If MSTR’s stock price rises, bondholders can convert their bonds into shares and make a huge profit. If the stock price doesn’t rise, MSTR will repay the principal and interest at maturity.
This is the famous “flying wheel”: issue bonds to buy coins, increase coin prices, drive up MSTR’s stock price, benefit bondholders, increase stock premiums, and then issue more bonds to buy even more coins.
This is what’s known as a “spiral upward” pattern. But wherever there’s a spiral upward, there’s also a downward spiral.
This type of collapse is called “forced deleveraging under liquidity depletion.”
想象一下,如果未来的某一年,比特币进入了漫长的横盘期(不需要暴跌,只需要横盘)。这时候,旧的债券到期了。债主们一看:MSTR的股价跌破了转股价格。
债主不是慈善家,他们是华尔街的吸血鬼。这时候他们绝不会选择把债券转成股票,他们冷冷地说:「还钱。要现金。」
MSTR有现金吗?没有。它的现金都换成了比特币。
这时候,MSTR面临一个绝望的选择:要么,借新债还旧债。但因为币价低迷,市场情绪差,新发债券的利息会高得吓人,直接吞噬掉那点可怜的软件业务现金流。
要么,卖币还债。
一旦MSTR被迫宣布「为了偿还债务而出售比特币」,这就是向市场发射了一枚核弹。
市场会恐慌:「死多头投降了!」恐慌导致币价下跌,币价下跌导致MSTR股价暴跌,股价暴跌导致更多的债券无法转股,更多的债主要求还钱。
这就是「索罗斯式」的狙击时刻。
这种暴雷姿势最凶险,因为它不需要比特币崩盘来触发,它只需要「时间」,当债务到期日遇上行情静默期,资金链断裂的声音,会比玻璃破碎还要清脆。
姿势三:杀人诛心
If the second posture is “no more money available”, then the third posture is “no one believes anymore”.
This is currently MSTR’s biggest risk, and also the blind spot that retail investors often overlook: the premium rate.
Let me do some calculations for you. Suppose you buy one share of MSTR for 100 dollars. But those 100 dollars actually only represent 50 dollars worth of Bitcoin. What’s the rest of the money?
It’s nothing. Or, to put it more nicely, it’s a form of “belief premium”.
Why would people be willing to pay double the price for Bitcoin?
Before physical ETFs like Blackrock’s IBIT came into play, there was no other choice—compliant institutions could only buy stocks. After physical ETFs were introduced, people continued to buy because they believed Saylor could use bonds to “support the currency” and thus outperform simply hoarding it.
But this logic has a fatal flaw.
MSTR’s stock price is based on the assumption that “I can borrow cheap money to buy Bitcoin”. Once this assumption is broken, the premium rate will return to normal.
Just imagine, what if Wall Street continues to pressure MSTR, and the White House forces MSTR to hand over its assets? What if the SEC suddenly issues a ruling saying that “holding currency by publicly traded companies is not compliant”? At that moment, everyone’s belief will collapse.
This kind of collapse is called “Davis Double Kill”.
那一瞬间,市场会问自己一个灵魂问题:「我为什么要花2块钱,去买1块钱的东西?我去买贝莱德的ETF不好吗?人家还是1:1的。」
一旦这个念头成为共识,MSTR的溢价率会从现在的2.5倍、3倍,迅速回归到1倍,甚至因为它是公司实体有经营风险,跌到0.9倍(折价)。
这意味着哪怕比特币的价格一分钱没跌,MSTR的股价可能直接腰斩。
这就是叙事的崩塌。它不像债务违约那样血淋淋,但它更杀人诛心。你看着手里的比特币没跌,但你账户里的MSTR却缩水了60%,你会怀疑人生。这叫「杀估值」。
姿势四:关门打狗
第四种姿势,最隐蔽,最不为人知,但也最具有讽刺意味。
现在MSTR正在拼命做什么?它在拼命做大市值,试图挤进更多的指数,比如已经挤进的MSCI股票指数和纳指,比如S&P 500(标普500指数)。
很多人欢呼:「进了标普500,就有几十万亿的被动资金必须买它,股价就能永动机了!」
老话说得好,福兮祸之所伏。
因为进入美股指数,MSTR早就不再是一个单纯的庄股,它变成了美股金融体系结构中的一颗螺丝钉。华尔街正通过左手做空MSTR,右手放出MSTR被踢出指数的新闻,带来散户恐慌性抛售。
MSTR is now completely out of control. It wants to use the money from Wall Street, but in the end, it’s trapped by the rules of Wall Street itself.
It tries to use Wall Street’s rules to get ahead, but ultimately, it may also die under those same rules.
Conclusion: The drama of power struggles within the financial world continues.
Michael Saylor is a genius… and also a madman. He understands the essence of currency depreciation and seized the opportunities of this era. He transformed an ordinary software company into a “Noah’s Ark” that carries the dreams of millions of investors.
But the amount of Bitcoin he owns far exceeds what his company can handle.
Many people in the market speculate that the U.S. government might invest directly in MSTR in the future.
This could be done either by using U.S. government bonds to replace MSTR’s shares, or by supporting MSTR in issuing preferred stocks backed by the state. In some cases, direct government intervention could even be necessary to improve MSTR’s credit rating.
This drama isn’t over yet. The power struggles between the old and new financial orders in the U.S. continue. MSTR’s structure is fragile—it operates on the principle of taking advantage of volatility when possible, and using short positions when needed.
If Wall Street removes one of MSTR’s key components, then the four scenarios we mentioned earlier—price crashes, debt defaults, disappearing premiums, and index strangulation—could lead to a short-term imbalance in MSTR’s structure.
But on the other hand, when all these elements work together, MSTR could become one of the most volatile assets in the global capital market.
That’s the charm of MSTR… and also its danger.