Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
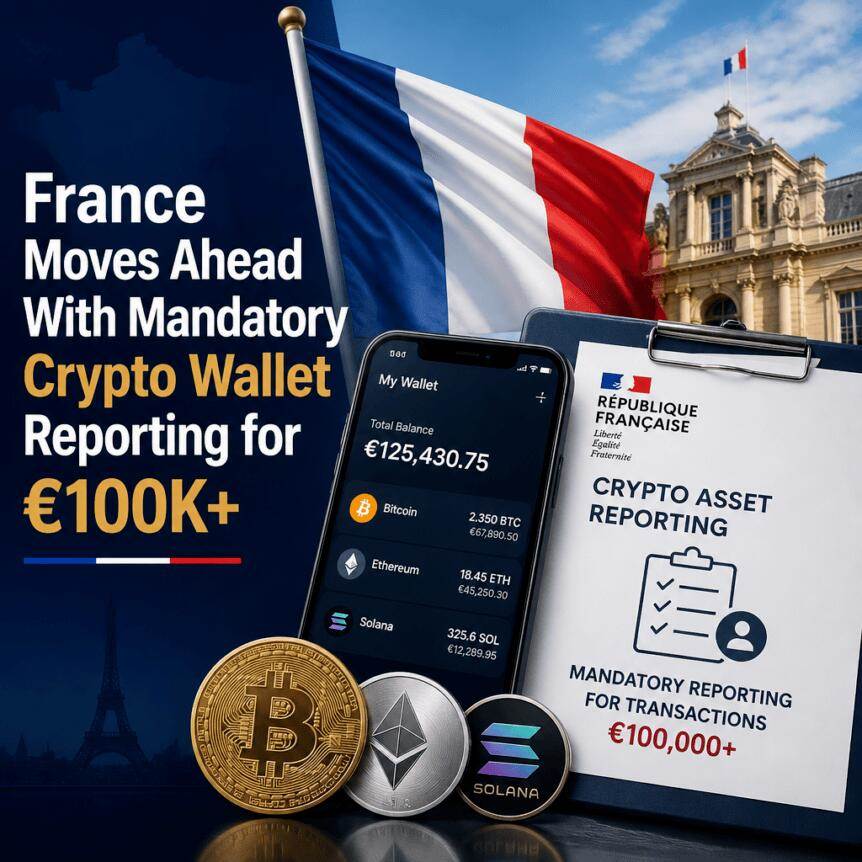
French lawmakers are pushing for tightening regulation of self-custodial cryptocurrencies, requiring holders to declare assets of more than 100,000 euros
French lawmakers are working to strengthen supervision of individuals 'positions in self-custodial cryptocurrencies. An amendment has been passed that would force individuals to declare crypto assets worth at least 100,000 euros or face penalties.
The proposal, numbered I-CF821, was passed by the Finance Committee of the National Assembly on Friday. The proposal targets crypto assets that are not held through regulated crypto asset service providers, including assets stored in personal wallets, and will insert new reporting obligations in the French General Tax Code.
Core Points
- Amendments require taxpayers to disclose self-custodial crypto assets equal to or greater than 100,000 euros.
- Declarations are based on asset values as of December 31.
- Non-compliance can trigger fines of up to 10,000 euros.
- Although the measure has been approved by the Finance Committee, it still faces parliamentary procedural obstacles as some provisions of the broader 2027 Budget Bill are rejected.
This French crypto policy initiative is consistent with broader efforts to narrow the gap between realized crypto benefits and those declared to tax authorities.
Specific requirements for amendment
According to the amendment passed by the Finance Committee, holders of crypto assets that are not held through crypto asset service providers must declare once their positions reach the threshold of 100,000 euros. This scope clearly includes cryptocurrencies that are kept by individuals themselves, such as assets stored in individuals 'wallets.
The sponsors of the amendment said the move was aimed at solving the problem of tax evasion. To support the policy, they cited a parliamentary investigation into taxes on high net worth individuals. According to reports, the survey found that the total amount of crypto capital gains in 2021 reached 3.5 billion euros, while only 400 million euros of crypto positions were declared to the tax authorities that year.
In legal terms, this text will add a provision to the French General Revenue Code. It will require disclosures based on the value of assets as at December 31 and set a penalty framework for non-declaration-citing fines of up to 10,000 euros.
Background of the proposal and overall thinking of the committee
The amendment was proposed by Charles de Courson, Jean-Pierre Bataille and Michel Castellani, three members of the French Liberal, Independent, Overseas Departments and Territories Parliamentary Group.
This was one of five crypto-related amendments approved by the Finance Committee last week. Previously, other proposals related to the French budget process were also under discussion, including changes such as imposing an exit tax on crypto positions of more than 800,000 euros when taxpayers migrate abroad, and tax deferral when ending conversion to fiat and stablecoins.
Legislative momentum is mixed after budget bill setbacks
Although the Finance Committee approved the crypto amendment on Friday, the broader legislative outlook is unclear. According to French public broadcaster LCP, lawmakers voted 31 - 3 to veto the revenue portion of the 2027 budget bill after committee approval.
According to French technology publication Clicanoo, lawmakers are scheduled to begin debating the revenue portion of the budget in the National Assembly on Tuesday, starting with the government's original draft. This order is crucial because crypto amendments need to be submitted again in parliamentary proceedings and approved before they can become part of final legislation. In other words, approval by key committees is an important step, but it does not guarantee that the proposal will survive the full legislative process-especially after the basic bill is partially rejected.
Why "self-custody" is at the heart of this policy push
The debate over crypto tax and compliance often focuses on the transparency (or lack thereof) provided by intermediaries. The amendment emphasizes regulation of assets not held at crypto asset service providers, which suggests that lawmakers believe there is a compliance loophole when individuals retain control directly through their personal wallets.
If reporting requirements are advanced, the burden of proof will shift to individuals, requiring them to disclose their positions to tax authorities, with a fixed valuation date of December 31. This design also means that taxpayers must be prepared to calculate the euro value of their crypto assets at the end of the year and then file a declaration when positions exceed the 100,000 euro threshold.
As a result, a large number of investors and traders who hold multiple self-managed assets may need to pay more attention to record-keeping and valuation methods because the policy includes financial penalties for undeclared behavior.
At present, readers may be most concerned about whether the amendment can pass through the remaining parliamentary stages after the revenue portion of the budget bill is rejected by the committee. The next development that needs to be watched is the steps of Tuesday's debate in the National Assembly and whether lawmakers will reintroduce and successfully incorporate encrypted reporting language into the final 2027 tax framework.