Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
 BTC
 ETH
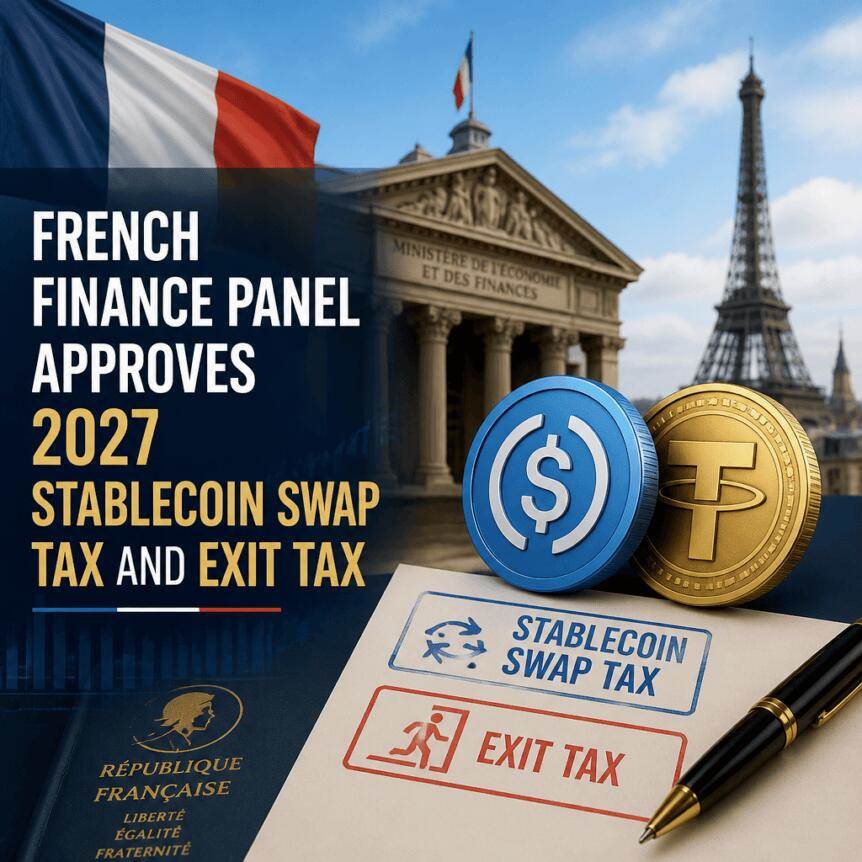
Finance Committee of the French National Assembly promotes new cryptocurrency tax measures
The Finance Committee of the French National Assembly has promoted new cryptocurrency tax measures aimed at tightening the recognition of capital gain triggers for certain digital asset transactions. The committee approved a tax proposal on the conversion of cryptocurrencies into stablecoins pegged to fiat currencies and expanded departure tax rules for high-net-worth taxpayers when they move overseas.
These changes were adopted through multiple amendments during the committee review process. If it eventually becomes law, investors could face capital gains tax obligations even if they have not converted assets into fiat currencies-raising practical questions for anyone using stablecoins as a store of value or liquidity management.
Core Points
The French Committee has approved an amendment stipulating that conversion of stablecoins pegged to fiat currencies will be regarded as a taxable event from January 1, 2027. The committee's document describes the current handling of such conversions as a "loophole" in legislation. Another approved measure allows taxpayers to carry forward realized cryptocurrency losses for up to 10 years. In addition, a departure tax amendment targets the issue of taxing unrealized gains on taxpayers whose households hold cryptocurrencies with a market value of more than 800,000 euros (approximately $895,000) when they move their place of residence abroad.
France brings stablecoin conversion into tax supervision
One of the core measures is amendment I-CF1826 submitted by French MP Nicolas Sansu on Wednesday. The proposal stipulates that starting from January 1, 2027, the conversion of cryptocurrencies into stablecoins pegged to fiat currencies will be regarded as taxable.
In the accompanying explanatory material, the current framework is described as a "loophole" in the legislation. The practical impact is straightforward: under the proposed rules, conversion to stablecoins pegged to legal currencies is no longer considered a non-taxable step, although certain interpretations under existing rules may allow it.
Regarding the determination of tax payable, the amendment states that taxable income should be calculated using the acquisition cost of the assets disposed of. For positions of the same token purchased at different prices, the document specifies the weighted average method to calculate the acquisition cost.
A broader legislative timetable is crucial for investors. The French National Assembly plans to begin reviewing the Finance Bill 2027 on Tuesday, October 13. If the bill is passed, taxpayers could trigger capital gains tax obligations due to the stablecoin conversion even if positions remain in the crypto ecosystem.
Taxable events that can be triggered without a "withdrawal"
The committee's stablecoin conversion rule is eye-catching because it targets the timing of moving value to a specific class of crypto assets, rather than traditional fiat withdrawals. According to the amendment, conversion into stablecoins pegged to legal currencies may be regarded as other disposal for tax purposes.
This difference is significant for users who rely on stablecoins for exchange operations, payment processes, collateral management or temporary portfolio positioning. Under the proposed framework, tax triggers could occur even if euros were not withdrawn into bank accounts, which could lead to a mismatch between the tax payable and the available liquidity available for payments.
While this measure does not mean that every stablecoin strategy will not work, it does increase the importance of careful record-keeping and cost base tracking-especially for investors who repeatedly rotate between tokens or perform multi-legged transactions that ultimately enter stablecoin.
Loss carry-over and expanded departure tax
The French committee also approved a measure that may reduce the risk of some investors being affected by market fluctuations. Amendment I-CCF798, introduced by Councilman Daniel Labaronne and passed Wednesday, allows taxpayers to carry forward realized cryptocurrency losses for 10 years.
Meanwhile, the committee approved a departure tax amendment on Thursday that would expand the tax on unrealized gains when certain taxpayers move their place of residence abroad. According to the description in the source material, this departure tax extension applies to taxpayers whose family cryptocurrency holdings have a value of more than 800,000 euros (approximately US$895,000) at the time of transfer of residency. For these families, moving overseas may become more expensive from a tax perspective-even if the benefits have not yet been realized through the sale of fiat currencies.
How does this move fit into broader EU cryptocurrency tax rules
法国并非孤立行动。在整个欧洲,针对加密货币活动的税收提议呈现出不同的形态,而法国委员会的方法因其专注于稳定币转换而显得尤为关键。
例如,源材料指出,希腊国家经济与财政部发布了一份草案,提议对个人加密货币资本利得征收10%的税款,年度收益高达500欧元(约560美元)的部分免税。与法国的转换方法不同,希腊草案被描述为不对加密到加密的交易征税。
同时,欧盟层面的报告规则正在重塑税务机关追踪加密货币活动的方式。法国及其他欧盟成员国必须根据欧盟《行政合作指令》(DAC8)第八次修正案实施税务报告。
根据DAC8规定,加密服务提供商必须收集用户的身份信息和交易数据,并向国家税务机关报告,随后这些数据将在成员国之间交换。报告要求已于2026年1月1日开始适用,涵盖2026年交易的首批信息交换需在2027年9月前完成。
这种时间顺序是重要的背景信息:法国拟议的稳定币转换税收变化针对的是如何定义应税事件,而DAC8则影响当局能够多大程度上准确地看到发生了什么。对于投资者而言,更清晰的应税触发点和不断扩大的报告能力相结合,增加了税务状况受到审查的可能性。
后续关注重点
As the committee's proposals move into broader parliamentary deliberations, the main uncertainty is whether stablecoin conversion rules and departure tax extensions will survive the full legislative process. French investors should pay close attention to the Finance Bill 2027 discussions that begin on October 13 and follow up on any amendments that clarify the definition of a "stablecoin pegged to fiat" in tax practice and how taxpayers plan for liabilities triggered by non-conversion into fiat currencies.