Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
 BTC
Can Bitcoin become a “currency”? The struggle between fixed supply and volatility
The role of Bitcoin as a “currency” has once again attracted attention. Two prominent figures engaged in a heated debate over whether Bitcoin’s fixed supply inevitably leads to significant price fluctuations, or whether the volatility will diminish over time as its adoption increases.
Saifedean Ammous expressed his views in his book “Bitcoin Standard”. In a post published on the X platform (formerly Twitter) on Tuesday, he argued that Bitcoin is already functioning as a medium of exchange. In his opinion, the key test isn’t whether Bitcoin is widely used for everyday payments today, but whether it can be monetized in a way that allows it to perform broader monetary functions in the future.
Ammous stated that even without widespread use in retail payments, the process of Bitcoin becoming a currency can still continue, and he expects the impact of volatility to reduce over time.
Ammous: Bitcoin can become a currency before it becomes ubiquitous
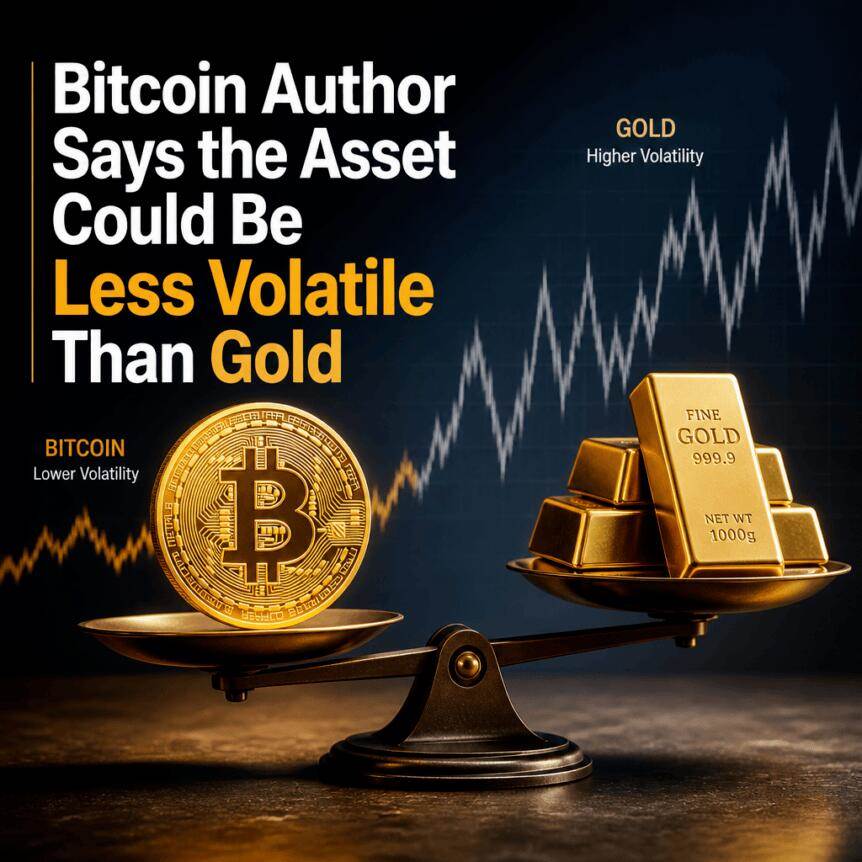
Ammous’ argument focuses on a practical difference: regardless of the current influence of Bitcoin as a daily payment method, the fact that Bitcoin can be used as currency already constitutes a significant advantage. He pointed out that as adoption increases and the trading mechanism becomes more stable, Bitcoin’s volatility may become less disruptive. In a post on the X platform on Tuesday, Ammous wrote that since Bitcoin’s volatility is lower than that of gold, it can serve as a medium of exchange. He also suggested that the process of Bitcoin becoming a legitimate currency asset is gaining momentum. He emphasized that the lack of widespread use as a payment method alone does not indicate that the process of Bitcoin becoming a currency asset is hindered.
Lawrence H. White believes that fixed supply hinders the creation of a stable medium of exchange.
Professor Lawrence H. White’s response is based on more traditional concerns about currency mechanisms. According to White—who cited Chapter 6 of his book “Better Money: Gold, Cash, or Bitcoin?” in a post on the X platform on Monday—the fixed supply of Bitcoin means it cannot adapt to changes in demand.
White believes that this volatility characteristic undermines Bitcoin’s suitability as a reliable medium of exchange. In the same thread, White added that stablecoins have “taken away Bitcoin’s trading volume,” linking Bitcoin’s role as a trading medium to the rise of assets designed to maintain price stability.
At the core of this debate lies a crucial trade-off: volatility versus monetary functionality.
The core of this controversy lies in a question that often arises among investors and developers: does a currency need to remain stable from the beginning, or can it become sufficiently stable (relative to its alternatives) as it becomes more widely used? Ammous’s framework suggests a gradual transition process. If Bitcoin’s price fluctuations decrease over time, as liquidity increases and market behavior changes, then its functionality as a currency could improve, even without it immediately dominating retail payments. White’s framework, on the other hand, argues that without an automatic supply response mechanism, Bitcoin may still not meet the level of reliability that people expect from a medium of exchange. Thus, these two perspectives differ not only in their views on Bitcoin’s current behavior, but also in their opinions on the timing and structure of the emergence of a “currency” market.
Prediction and Scale: Can Bitcoin Outperform Gold?
Although Ammous and White’s discussions were conceptual in nature, other commentators have attempted to quantify where Bitcoin might go if its adoption continues. The article mentions André Dragosch, head of research at Bitwise Europe, who told media in May 2025 that Bitwise’s internal forecasting model indicates that Bitcoin could reach $1 million by 2029. This level would mean that Bitcoin’s market value would be equal to that of gold.
This expectation faces the challenge of reality in terms of scale. The article notes that at that time, the total market value of Bitcoin was approximately $1.6 trillion, while that of gold was nearly $29 trillion. For Bitcoin to surpass gold in terms of market value, it would need to grow by at least 18 times.
Additionally, in April 2025, Adam Back, CEO of Blockstream, believes that Bitcoin may eventually become competitive with gold as a currency hedge tool—he cites global financial instability and rising inflation of fiat currencies as key drivers. These predictions suggest that Bitcoin’s role will shift towards macro hedging, rather than replacing gold or fiat currencies in daily transactions.
For readers, the message is clear: even if Bitcoin becomes more “monetaryized” within broader investment portfolios, the path it takes to transition from being a medium of exchange for everyday payments to a true currency may differ from the path taken when it simply aims to reach certain price targets.
Key areas of future observation
Ammous and White disagree on two issues: whether Bitcoin’s volatility can be reduced enough to support broader exchange functions without losing its supply flexibility; and whether stablecoins continue to divert Bitcoin’s activity through volume metrics. For traders and long-term holders, the signals that need to be monitored include changes in volatility compared to major benchmarks, as well as evidence of a shift in Bitcoin’s usage from transactions to more permanent monetary needs.