Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
每当看到有人因为一条关于X的推文就押注加密货币,让资金流动起来时,我都会觉得好笑。我也曾有过这样的经历。我记得五年前,我把一个月的大部分积蓄都投进了狗狗币,因为,嗯,埃隆·马斯克在推特上提到了它。那时候我甚至都不知道加密货币到底是什么。
但有些资金进入加密货币领域并非靠一条推文、一期播客或一次会议主题演讲就能实现。它需要更多。或许联邦监管机构的备忘录、风险评估以及一个值得信赖的平台会有所帮助。
美国商品期货交易委员会(CFTC)的最新声明允许在CFTC注册的交易所交易现货加密货币产品,这正是该声明的内容。
美国商品期货交易委员会(CFTC)的默许可能会促使美国最正规的衍生品交易市场——芝加哥商品交易所(CME)——上市加密货币。如果这种情况发生,将会打开加密货币市场的大门,吸引大量资金从传统市场涌入加密货币领域。
在今天的深度分析中,我将解释此举如何能让加密货币流入美国存放其最受信任资产的同一栋大楼,以及这为什么重要。
Before the emergence of today’s seamless financial markets, people were reluctant to engage in financial product transactions. The problem wasn’t a lack of buyers and sellers; there were plenty of them in the market. The issue was a lack of trust—everyone worried about what would happen if the other party couldn’t pay.
Now, you don’t need to worry about this anymore. This is thanks to a modern invention that’s often overlooked: modern stock exchanges. They establish trust by regulating contracts, enforcing disclosure requirements, and overseeing behaviors. These developed markets incorporate all these elements into mechanisms like “clearing” and “margins,” thereby preventing settlement risks from hindering traders’ enthusiasm every day.
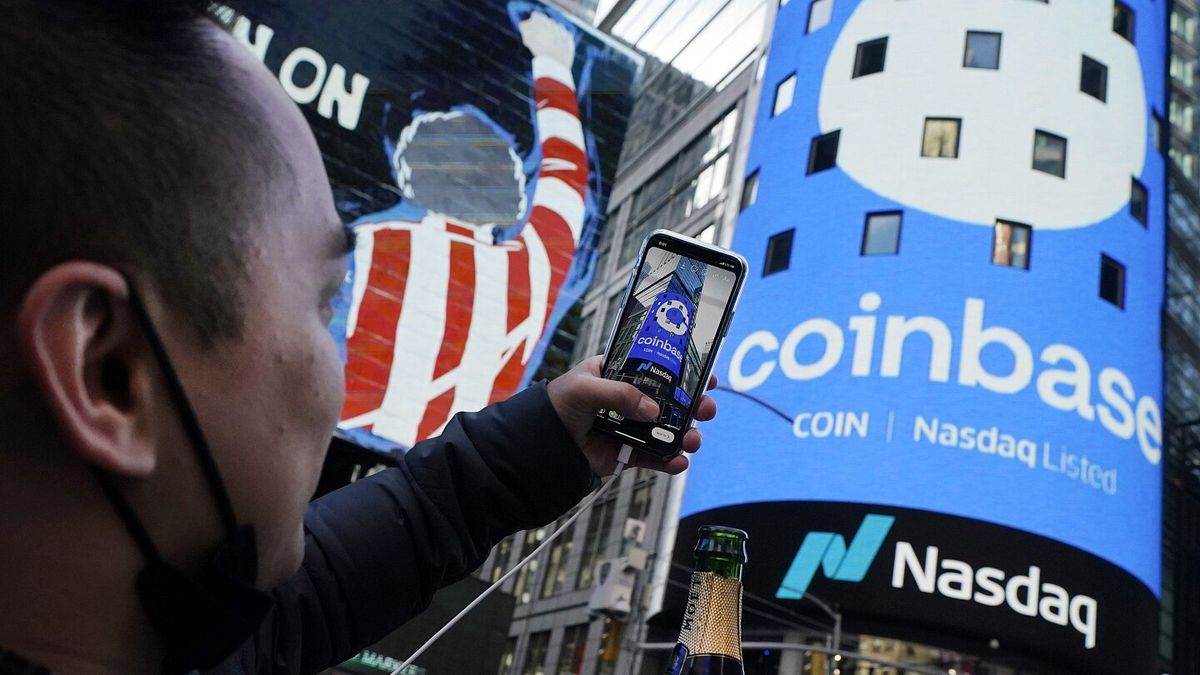
Although people talk about systems where trust isn’t needed, trust remains difficult to establish in the cryptocurrency market. The latest announcement from the U.S. Commodity Futures Trading Commission (CFTC) might help fill this gap.
Caroline Caffet, acting chairperson of the CFTC, said, “The listing of spot cryptocurrency products will now be regulated by the CFTC, which is the first time such activities are being regulated at the federal level.” She expects this move to provide Americans with “more choices and easier access to a safe, regulated American market.”
This update has redefined the boundaries of where cryptocurrencies can move, as regulators are working hard to integrate digital assets into the mainstream markets of the world’s largest economy.
Just look at the data from the Chicago Mercantile Exchange (CME), and you can see how large of a potential market it could be for spot cryptocurrency trading.
On November 21st, the trading volume of cryptocurrency futures and options on the Chicago Mercantile Exchange (CME) reached a record high, with 794,903 contracts traded. This figure surpassed the previous record set on August 22nd, which was 728,475 contracts. The market also reported the number of transactions that have moved into its regulated framework since the beginning of the year. The average daily trading volume so far this year was 270,900 contracts, with a nominal value of approximately $12 billion, representing a 132% increase from previous years. Meanwhile, the average number of open positions so far this year was 299,700 contracts, with a nominal value of $26.6 billion, representing an 82% increase. Even under assumed conditions, if the CME converts only 5% of its nominal trading volume into physical transactions, that would still amount to $600 million per day. If the conversion rate reaches 15%, then the figure could approach $2 billion per day. But what are the advantages of having physical cryptocurrencies and derivatives under the same umbrella at the CME? First of all, it reduces the distance between traders’ positions and hedging strategies. Currently, many traders keep their cryptocurrency exposures in one place, while hedging positions are managed elsewhere. They may trade cryptocurrency futures on the CME because it is regulated and cleared, but their physical exposures may come from ETFs, principal brokers, or cryptocurrency exchanges. Switching between different trading platforms doesn’t necessarily increase monetary costs, but it can lead to non-monetary complications. For example, it involves dealing with more counterparties, incurring higher operating costs, and facing more risk points.If a regulated market can accommodate both the spot market and derivatives markets, hedging becomes much more convenient, and long-term position management can be carried out more efficiently. Both aspects involved in trading decisions can be managed under the same compliance framework—including aspects such as margin requirements, reporting, and monitoring. Platforms like Coinbase (along with its derivatives trading platforms), Kraken, and Robinhood, which are native to the cryptocurrency industry, benefit from offering all these services on a single platform. Another advantage is that this changes the way large traders define “spot” transactions. As individual traders, when purchasing spot assets on cryptocurrency exchanges, they often focus on the price of the asset itself. However, when investing in spot assets through funds, traders consider factors such as custody, settlement, reporting, and the stability of the market under pressure. Derivatives exchanges like the Chicago Mercantile Exchange have established systems that help enhance market confidence. The clearing systems, margin mechanisms, and monitoring measures provided by the CME offer large fund managers a regulated safe haven, allowing them to invest their funds in the volatile cryptocurrency market during uncertain times. Hundreds of billions of dollars may flow from large fund managers. Just in the United States, the issuers of spot Bitcoin ETFs hold assets worth over $112 billion. Since their establishment in January 2024, these issuers have received over $57 billion in investments.An ecosystem that combines physical assets with derivatives could encourage some investors to shift from holding assets through funds to trading them on the market. For fund companies, this could lead to cost advantages and greater control over their investments.
ETFs charge fees, but their purpose is still to hold the underlying assets. Although their trading methods are similar to those of stocks, they still rely on the infrastructure of the stock market during trading hours. For fund companies that need to manage risks and take advantage of inefficient market opportunities, they prefer platforms that offer all-day hedging, strict basis-point execution, frequent rebalancing, or market-making capabilities.
The third advantage is operational efficiency.
The U.S. Commodity Futures Trading Commission interpreted this as a response to recent offshore exchange incidents, arguing that American citizens deserve access to markets that ensure consumer protection and market integrity. However, the real issue behind this is leveraged trading. Pham pointed out that Congress already initiated reforms after the financial crisis, and he mentioned that Congress originally hoped that leveraged trading in retail commodities would be conducted on futures exchanges. However, over the years, no clear regulations have been established.
Leveraged trading is the breeding ground for the worst incidents in the cryptocurrency industry. Just a few days ago, on October 10th, the most severe liquidation event in cryptocurrency history resulted in the loss of $19 billion. If leveraged trading could be conducted on platforms that emphasize monitoring, margin discipline, and liquidation procedures, transparency could be improved at least to some extent. At that time, traders would no longer have to deal with opaque offshore liquidations, but rather with transparent margins, known counterparties, and rules that cannot be changed arbitrarily.
This update even led cryptocurrency platforms to promise fair treatment for both individual investors and large traders.
Shortly after the CFTC issued a statement, US-regulated derivatives exchange Bitnomial claimed that it would provide “equal and fair treatment” to both retail and institutional orders, without any preferential treatment being given to any particular type of orders.
Considering all these factors, the CFTC’s actions seem promising, as they could make spot cryptocurrency trading more accessible and reliable, something that was previously only possible for large-capitalized traders.
However, the CFTC’s statement won’t make the CME become a mature spot cryptocurrency exchange tomorrow. Even if the market develops in this direction, the initial version may still be conservative due to design considerations: there will be fewer trading options, strict definition of leverage terms, and transactions will be conducted through existing intermediaries within the CME ecosystem.
This is because the establishment of trust is a process that happens gradually over time. Even in history, trust was typically built through the implementation of various safeguards, rather than through random posts about X.