Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
 BTC
According to Glassnode, the cryptocurrency derivatives market is becoming more active, with a rise in the number of perpetual contracts. Market participants expect significant fluctuations by the end of this year. The number of open positions in Bitcoin perpetual contracts has increased to 310,000 BTC, and the funding rate has doubled, indicating a bullish trend for the market at the end of the year.
The number of perpetual contracts (OI) has increased from 304,000 BTC to 310,000 BTC. Glassnode reported that the price reached $90,000 on Monday.
The financing rate also rose from 0.04% to 0.09%, indicating that derivatives traders expect market volatility by the end of the year.
Glassnode stated, “This indicates an increase in long positions with leverage, as traders are preparing for potential market movements at the end of the year.”
Bitcoin perpetual contracts are non-expiry futures that can be held indefinitely. They track the spot price of Bitcoin using a mechanism called the funding rate, which is a regular payment between traders holding long and short positions.
An increase in the financing rate suggests bullish sentiment.
When the financing rate rises, it usually means that the price of perpetual contracts is higher than the spot price. More traders become bullish, as they are willing to pay a premium to hold long positions.
However, it could also indicate potential market overheating, as extremely high rates may suggest excessive leverage for long positions, leading to risks of corrections.
As of the time of publication, the price of Bitcoin has not broken through the $90,000 mark and has fallen back to $88,200.
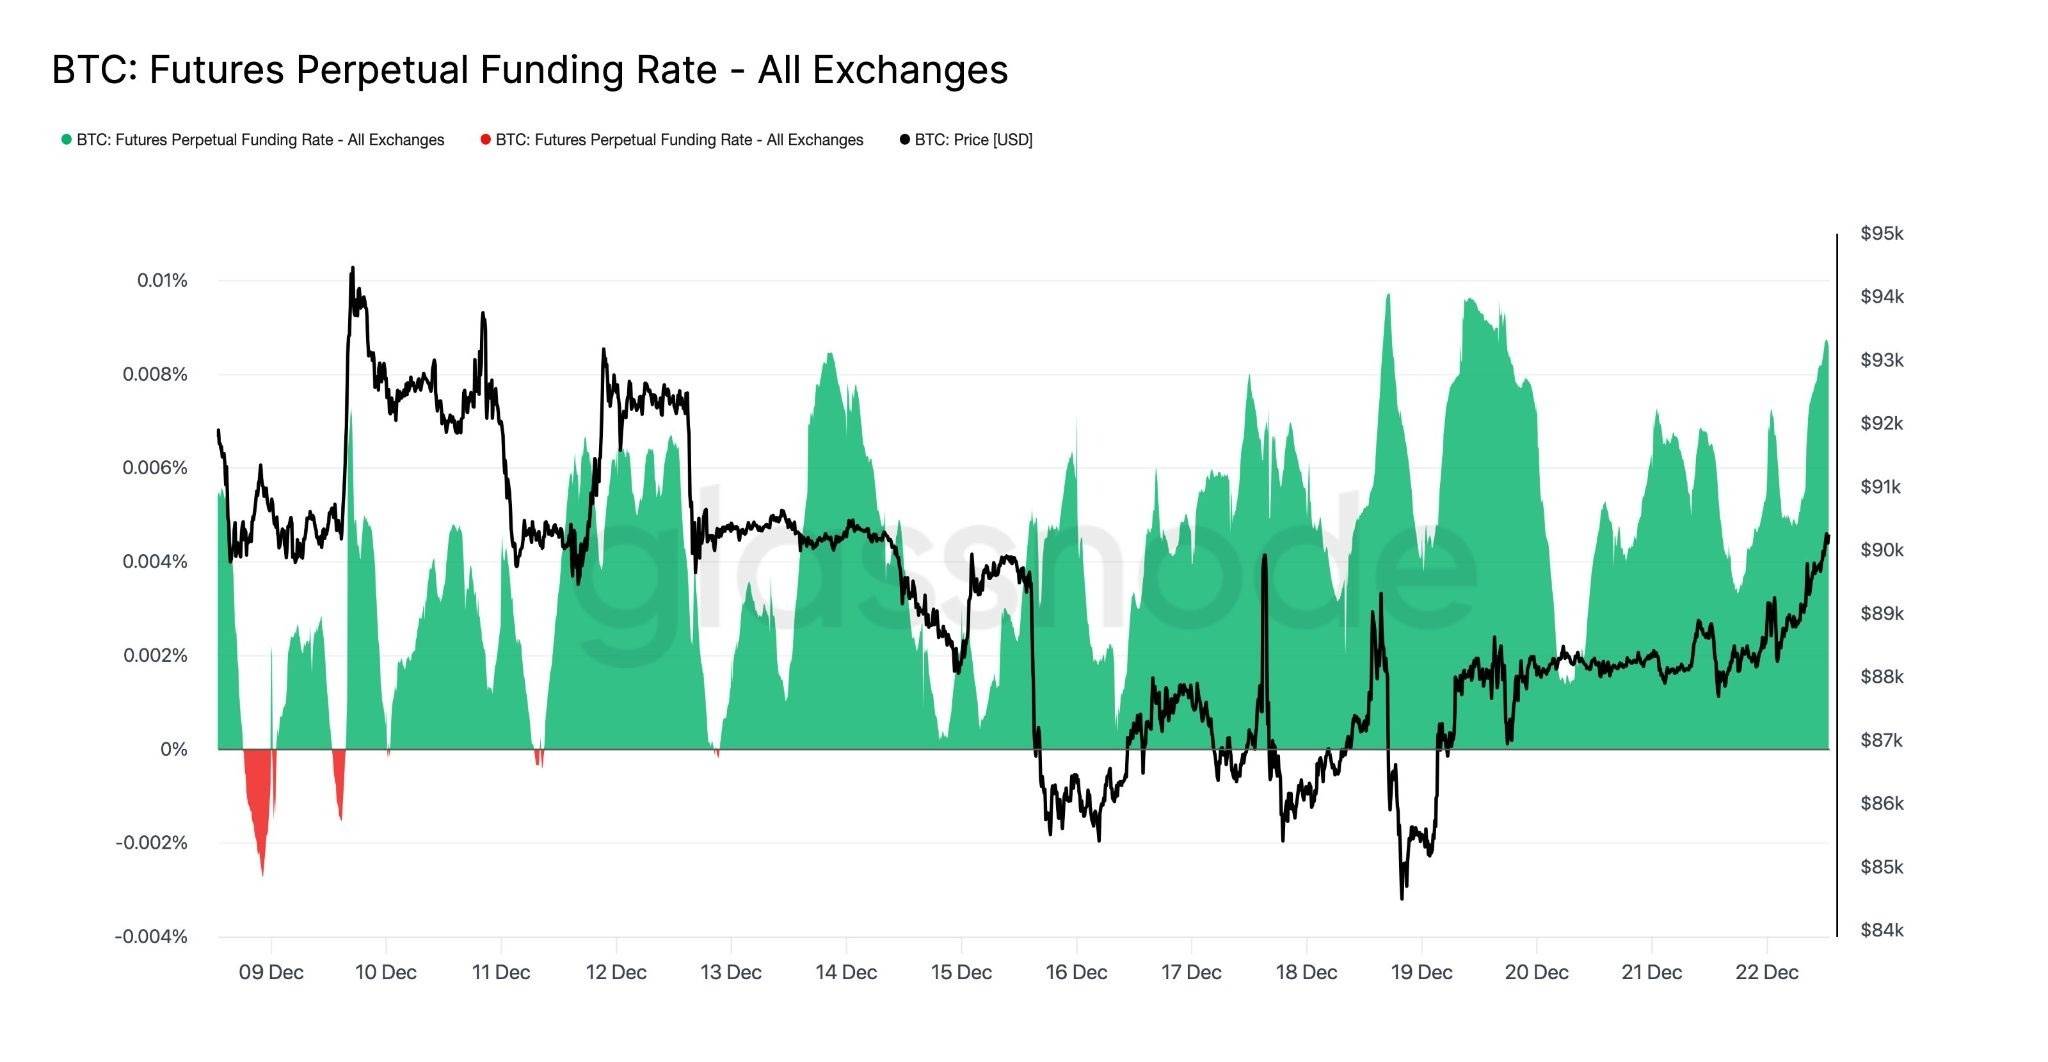
The prepaid interest rate for Bitcoin has recently increased. Source: Glassnode
A large number of options expire at the end of the year
On Friday, December 26th, a large number of Bitcoin options will expire at the end of the year, which could exacerbate market volatility.
Options contracts worth over $23 billion are about to expire, making this one of the largest expiration events in history. Expiration events at the end of quarters and years are much larger than those that occur weekly or monthly.
According to Deribit, call options are concentrated around the strike prices of $100,000 and $120,000, while put options are concentrated around $85,000.
Currently, the ratio of put/call options is 0.37, meaning there are far more long positions than short positions. According to Coinglass data, the maximum loss point is currently $96,000.
If the spot price does not increase, most of these contracts will become worthless when they expire. The gap of $7,500 indicates that calls with high strike prices are overly optimistic and will ultimately lead to losses.
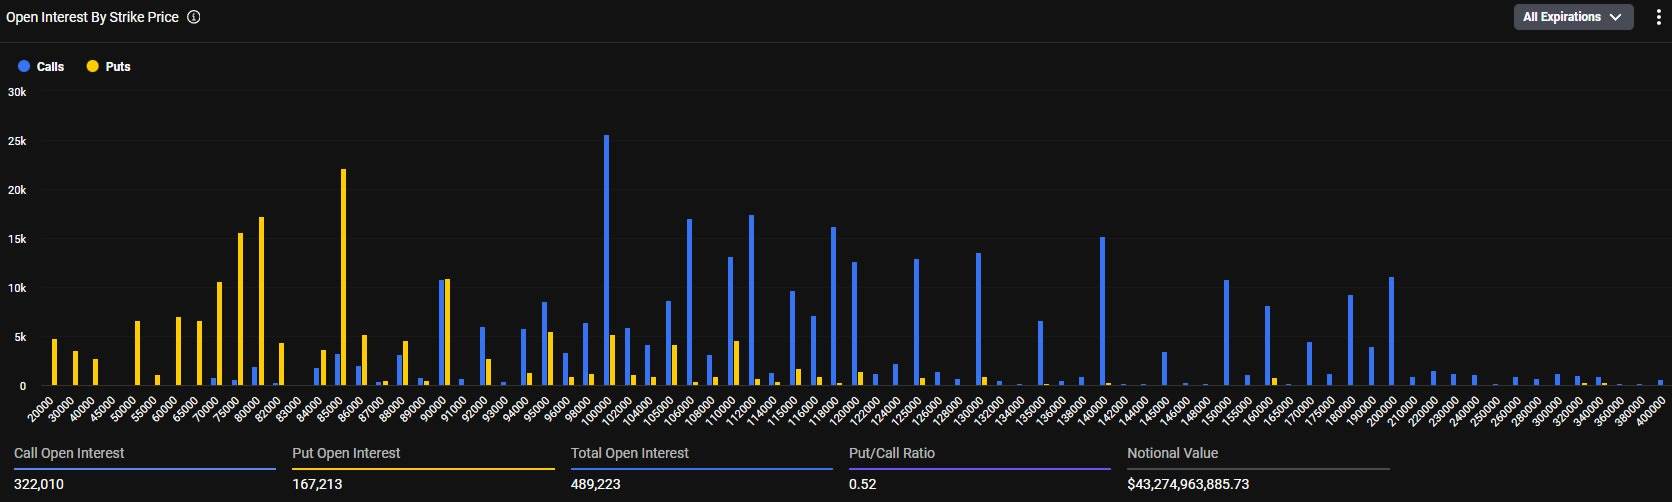
There is a large number of open contracts with high strike prices. Source: Deribit