Exchange Ranking
 Top Exchanges
 24h Volume Ranking
 Popularity Ranking
 Exchange BTC Balance
 Proof of Reserves
 Decentralized Exchanges
 Funding Rate
 Funding Heatmap
 Liquidation Data
 Max Pain
 Long/Short Ratio
 Whale L/S Ratio
 Binance/Okex/Huobi L/S
 Bitfinex Margin L/S
 ETF Tracker
 Solana ETF
 XRP ETF
 Hong Kong ETF
 Bitcoin Treasuries
 Crypto Reversal
 Ethereum Reserves
 HyperLiquid Wallet Analysis
 Hyperliquid Whale Watch
 Large Transactions
 On-chain Movement
 Bitcoin ROI
 Stablecoin Market Cap
 Options Analysis
 News
 Articles
 Economic Calendar
 Features
 Wallet
 Contract Calculator


 Security
 Collections
 Watchlist
 Following
As the launch date of Lighter approaches, there is a rapid divergence in market opinions regarding its valuation. Some believe that Lighter is merely another perpetual contract-based exchange, and they worry that it may not be able to challenge Hyperliquid’s dominant position. Others, however, see signs of potential growth based on recent data such as blockchain activity, market depth, and user numbers. Currently, most expectations focus on a valuation range of under a billion dollars. However, if trading volume increases, ecosystem collaborations are established, and incentive mechanisms are implemented effectively, Lighter’s positioning may be re-evaluated. Its potential valuation could reach several billion dollars, far exceeding the simple concept of launching an ordinary Perp-based exchange.
Note: I am an early user of Lighter (having received 644.3 points), so I have a high chance of receiving airdrops. The above information is solely my research and opinion, and should not be considered investment advice.
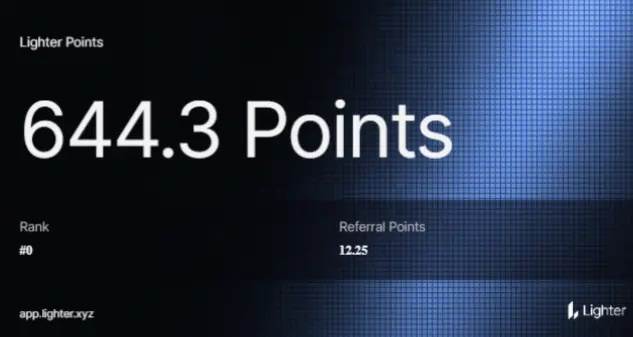
My Lighter points
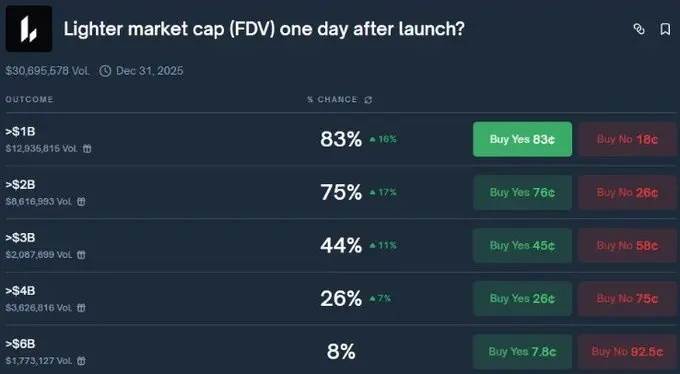
In my opinion, the current situation can be summarized as follows: Based on transactions on Polymarket, the estimated valuation of Lighter ranges between 2 billion and 3 billion dollars (at least according to current trading prices).
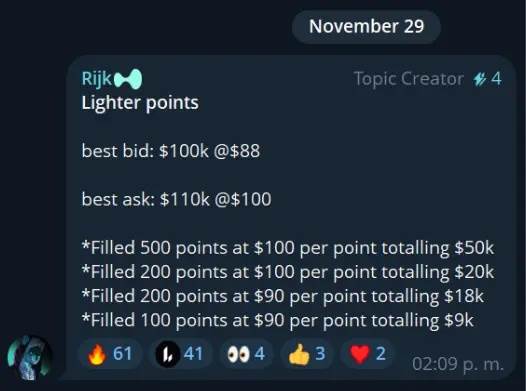
In the over-the-counter market, Lighter’s points are traded at around $90 per unit. If calculated based on approximately 11.7 million points, the value of the airdrop would be about 1.05 billion dollars.
If this portion of the airdrops accounts for approximately 25% of the total token supply, then the fully diluted valuation of Lighter would be around 4.2 billion dollars.
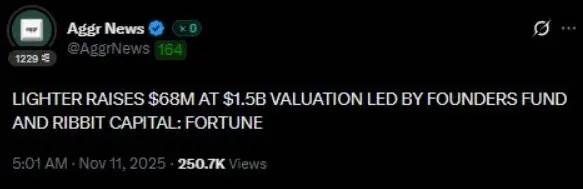
Lighter 此前完成 6800 万美元融资,对应估值约 15 亿美元,由 Founders Fund 与 Ribbit 领投(据 Fortune 报道)。
Founders Fund 在早期押注品类级公司方面有着长期而突出的记录,曾投资过 Facebook、SpaceX、Palantir、Stripe、Airbnb 等标志性企业。
另外,$LIT 在盘前市场的定价大致对应 约 35 亿美元的 FDV,这一价格可视为一个实时的市场参考信号(尽管仍处于早期阶段,且并不完全精确)。
所以,我对它的判断框架其实很简单:15 亿美元可以视为估值下限(偏熊区间,由 VC 融资轮定价锚定)。30 亿–42 亿美元属于熊市到基准区间(预测市场、盘前价格、以及积分反推估值大致集中在这里)。
● 真正的核心问题在于:基于基本面与催化因素,Lighter 是否配得上重估至 60 亿–125 亿美元甚至更高的区间。
这篇分析的目的,正是尝试把这些问题顺着逻辑讲清楚:Lighter 到底是什么产品、数据层面释放了什么信号、哪些估值框架是合理的,以及哪些催化剂可能推动它进一步向上重估。
1、一个关键的误解:Lighter 和 Hyperliquid 并不是同一类产品
我目前找到的最清晰的心智模型是:
● Hyperliquid is building a native Web3 liquidity layer. Its main source of revenue comes from retail transaction fees, along with additional benefits derived from ecosystem-level network effects.
● Lighter, on the other hand, is developing a decentralized trading infrastructure. Its long-term goal is to connect with fintech companies, brokerages, and professional market makers. At the same time, it aims to minimize execution costs at the retail level—in some spot markets, fees can even reach zero.
From this perspective, the problems they address, the customer base they serve, and their long-term business strategies are fundamentally different.
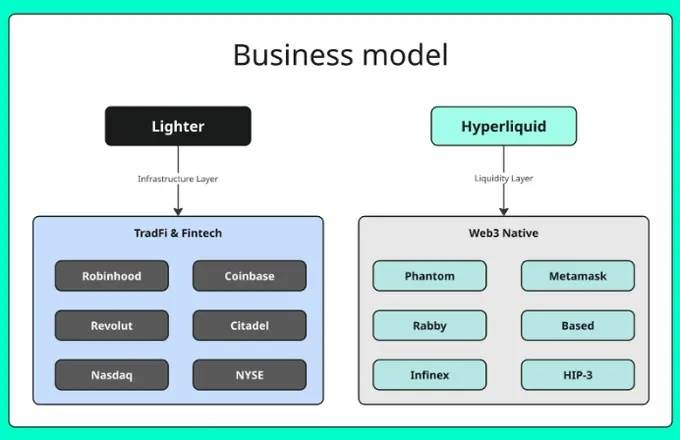
The business models of Lighter and Hyperliquid differ significantly. This distinction is important because it determines where the valuation ceiling lies.
If Lighter were simply another perpetual contract exchange, then its valuation would be determined by similar standards applied to other perp-based exchanges. But if it represents a trading infrastructure that can be integrated by large distribution channels like brokerages and fintech companies, then its valuation ceiling will be based on entirely different rules.
2. Current situation of Lighter (important numbers)
Here are the current key metrics:
● TVL: $1.44 billion
● LLP TVL: $698 million (used for execution/stability purposes)
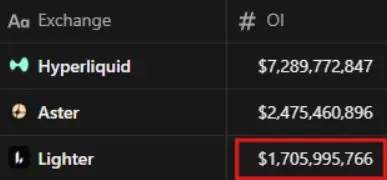
● Open positions: $1.7 billion
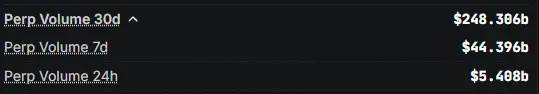
● 成交量: $5.41B(24 小时)/$44.4B(7 天)/$248.3B(30 天)
● 收入: 约 1,380 万美元(30 天)/ 约 1.679 亿美元(1 年)
这些数字给人的感觉很重要:
● 这已经是真正的规模了。每月2480亿美元的交易量绝非业余爱好。
● 未平仓指数虽然有意义,但并不表明“距离破产清算只有一步之遥”。
● TVL 足够高,以至于 Lighter 可以自信地谈论自己是一个可靠的场所,因为规模和可靠性才是机构真正关心的。
风险理性校验:OI / TVL(未平仓合约 / 总锁仓量)
衡量杠杆水平与流动性匹配度的一个快速方法,是计算 OI/TVL(未平仓合约除以 TVL)。基于当前快照数据:
● Lighter:1.71B / 1.44B ≈ 1.18
● Hyperliquid:7.29B / 4.01B ≈ 1.82
● Aster:2.48B / 1.29B ≈ 1.92
直观来看,Lighter 的 OI/TVL 明显更低,意味着在相对可控的杠杆水平下,拥有更充足的流动性缓冲。这种结构并不追求极限效率,而是更偏向稳健执行与系统韧性——这与其「基础设施型交易系统」的定位是相互一致的。
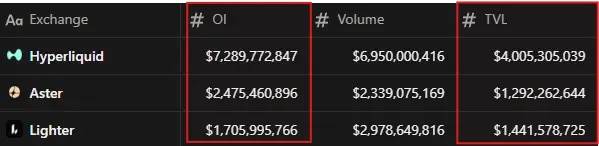
Key conclusions: Lighter already has a considerable number of open contracts, but compared to its liquidity level, the overall value of its market is not overly inflated. Compared to similar products in the same segment, its risk profile is more controlled and stable.
3. Spot market: The key factor driving further increases in TVL is the availability of spot trading options. This aspect may be undervalued by the market.
Perpetual contracts can indeed generate large volumes of transactions, but it’s often the spot market that truly captures “sticky funds” – especially when the trading platform offers significant advantages in terms of execution speed and costs. Additionally, spot trading significantly expands the potential user base: for new users, spot trading provides a lower threshold for entry; for market makers, it offers more reasons to hold assets on the platform over the long term.
Currently, ETH is the only spot asset that has been launched. This isn’t a limitation, but rather a starting point. What truly deserves attention is the fact that the “track” for spot trading is now established, and the product itself has the structural foundation to expand smoothly as more assets are added to the platform.
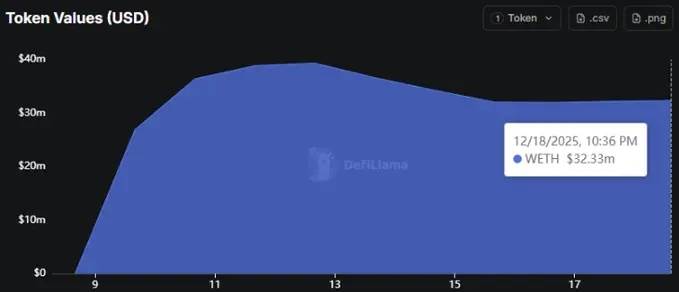
Diagram showing the value of Lighter’s spot tokens (WETH) (Source: DeFiLlama)
Even though only ETH is currently available, data from DeFiLlama shows that Lighter’s spot trading sector has accumulated approximately $32.33 million in WETH value (Snapshot Date: 2025/12/18).
This is still in the early stages, but the direction is correct: funds have begun to flow into spot trading. If Lighter continues to introduce dozens, or even hundreds, of new spot assets over time, then spot trading will become a real driver of TVL growth, rather than just an additional feature module. More importantly, the fact that ETH spot trading has zero transaction fees is already a significant advantage. As long as execution quality remains stable (with consistent spreads and reliable transactions), it will naturally attract active traders and institutions who will shift their high-frequency strategies and spot-perpetual arbitrage trades to Lighter. The result is a positive feedback loop: more transactions → more inventory → deeper liquidity. The conclusion is clear: the launch of spot trading is a major milestone. ETH is just the first step; the real potential for growth comes after the expansion of the spot asset catalog, as the platform becomes the default place for “trading + holding” on the chain. By 2026, if tokenized assets continue to move online, the platform that takes the lead in this area will not only gain more trading volume, but also access a new growth trajectory that most PERP DEXs are yet to prepare for.
关键不在叙事,而在计分板。而从数据上看,Lighter 已经走在前面。
RWA 领导力:数据在说话
Lighter 已经在链上 RWA 永续合约的未平仓合约(OI)与成交量两项指标上同时领先。这一组合非常关键:
● 未平仓合约(OI) 告诉您交易者在一段时间内持有的风险敞口大小。
● 成交量可以告诉你每天的交易活动量。
当一个交易场所在两项指标上同时领先,通常意味着交易者并非「试水」,而是已经将其作为该产品线的主要阵地在使用。
这也是为什么,RWA 更像是 Lighter 的结构性机会:它不是追逐热点,而是在一个即将放大的市场里,提前卡位。
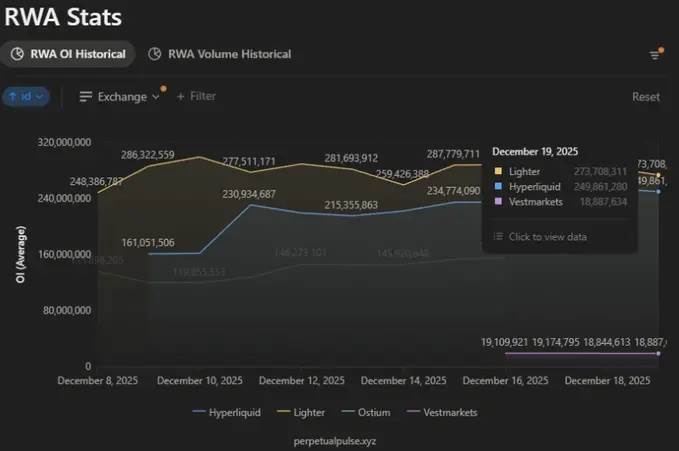
RWA 未平仓合约(Open Interest):Lighter 领跑该赛道(来源:PerpetualPulse.xyz)
在当前快照中,RWA 永续合约的未平仓规模大致为:
● Lighter:约 2.73 亿美元
● Hyperliquid:约 2.49 亿美元
这一差距之所以重要,在于 RWA 仍处于早期阶段。在早期市场中,流动性往往呈现高度集中的特征:
当某一交易场所率先聚集起规模化流动性时,点差会收敛、成交质量会改善,而更好的执行体验又会反过来吸引更多资金与交易量,形成自我强化的正反馈。
从这个角度看,Lighter 在 RWA OI 上的领先,并不只是一次静态排名,而更像是潜在复利效应的起点。
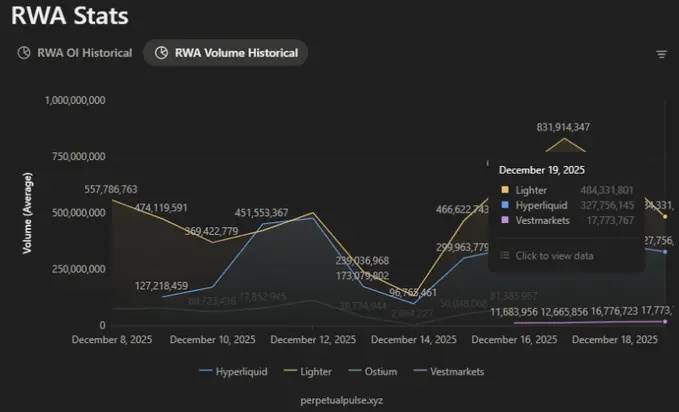
RWA 成交量:Lighter 在活跃度上同样领先(来源:PerpetualPulse.xyz)
从成交量看,这一趋势更加清晰:
● Lighter:约 4.84 亿美元
● Hyperliquid:约 3.27 亿美元
这正是早期产品–市场匹配(PMF)的典型形态:一个新类别开始成形,而某一交易场所率先吸走不成比例的交易活跃度。当使用频率与执行体验在同一平台持续累积,领先优势往往会被进一步放大。
市场规模被低估了
值得拉远视角看的是:代币化 RWA 并非小众赛道。在公链上,它已经是一个数十亿美元规模的市场,而且增长曲线仍然向上。这意味着,率先建立流动性、执行质量与用户习惯的平台,不只是赢下当下的交易量,更是在提前锁定一个仍在扩张中的长期增长通道。
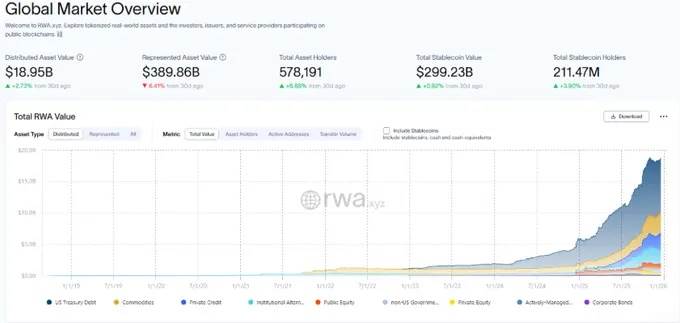
「Global Market Overview」仪表盘(来源:rwa.xyz)
The scale of tokenized RWA on public chains has reached approximately $18.9 billion, and it is still in its early stages.
This is important because RWA is one of the few narratives that don’t require “attentiveness” from the crypto community. It can expand outwardly, bringing real-world assets and transactions into the chain, achieving incremental growth rather than intense competition.
Why is this a significant catalyst for valuation?
The perpetual contracts for RWA have already demonstrated real demand; but the next step is even more crucial: physical RWA.
Perpetual contracts are good for speculation, while physical RWA is key to expanding the user base.
If Lighter can be among the first to offer trusted physical RWA trading (tokenized stocks/futures/commodities), while also maintaining high execution quality and institutional-level reliability, then this isn’t just adding a new feature, but actually expanding the market served by the product.
This also aligns with Robinhood’s narrative: once tokenized stocks become a real product distribution channel, the value of “backend exchanges/infrastructure layers” will increase significantly—because in the trading sector, distribution capabilities are the hardest-to-build competitive advantage.
The roadmap supports this direction.
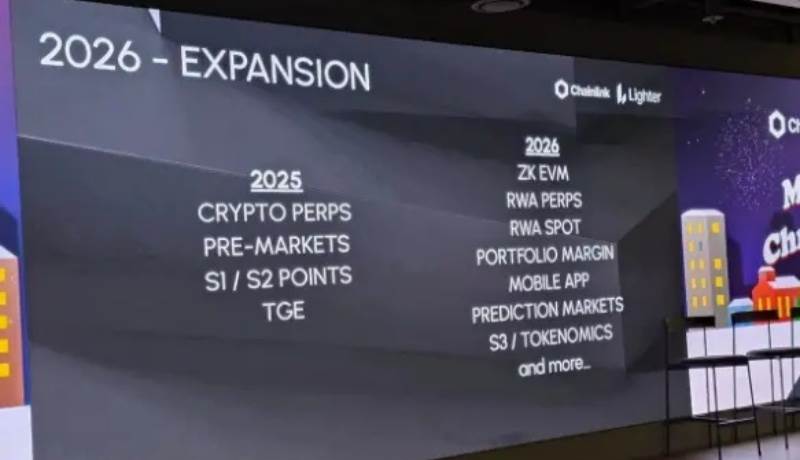
From the product roadmap, it seems that Lighter aims for 2026: deeper expansion of RWA, along with the necessary capabilities to support its scaling (mobile versions, portfolio margining, predictive markets, etc.).
This isn’t a one-time initiative, but rather a continuous expansion of the product’s scope.
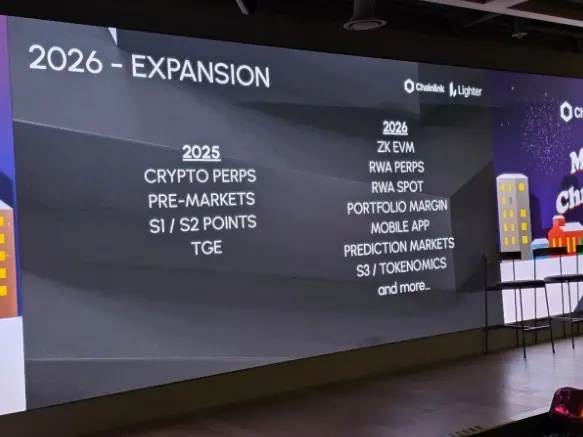
Chainlink × Lighter 首尔线下活动「2026 – Expansion」路线图幻灯片
如果 RWA 是 2026 年最重要的主题之一,那么 在早期就切入、且已经在 OI 与成交量上取得领先,本身就是一个极强的起手式。
结论很明确:RWA 并不是 Lighter 的「支线任务」。相反,它更像是 2026–2027 年实现超额增长的最清晰路径——因为这条路径将 Lighter 从纯加密原生的永续合约市场,扩展到更广阔的代币化金融产品世界。
5、Robinhood 对齐叙事:为什么「分发」会改变一切
Robinhood 是目前桌面上最干净、也最具想象力的分发楔子:
● 约 2600 万有资金的账户、
● 约 3330 亿美元的资产管理规模(AUM)
● 已成熟的模式:将订单流路由给大型做市商(典型的 Citadel 式流量结构)
一旦 Robinhood 成为代币化资产的真实分发渠道,那么提供执行与结算轨道的后台交易基础设施将变得极其有价值——因为在交易领域,分发能力始终是最难构建的护城河。
如果 Lighter 能成为 代币化资产 / 永续合约 / 类结算流量 的后台轨道之一(哪怕只是部分参与),其影响并不是「多了一些加密用户」,而是:通过一个熟悉的前端 UI,将全新的流动性引入链上市场。
这对估值的意义在于,它正面攻击了多数 Perp DEX 面临的最大天花板:Web3 原生流动性很大,但相较于传统金融的分发能力,仍然是有上限的。
而市场往往不会等到一切尘埃落定。哪怕这种叙事只是「有一定概率走向主流」,也足以触发重新定价——因为 加密市场定价的是概率,而不是确定性本身。
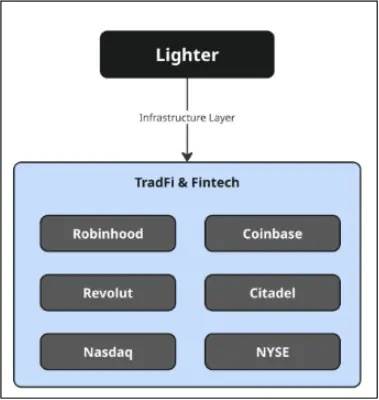
Lighter 的「TradFi & Fintech」基础设施定位(来源:X @Eugene_Bulltime)
6、估值:一个不靠「信仰」的简化框架
我更倾向于用锚点 + 现实校验来做估值。
估值锚点(市场已经给出的信息)
● 15 亿美元 FDV:下限 / 熊市锚点(来自 6800 万美元融资轮的 VC 定价)。跌破这一水平,意味着该轮融资从一开始就处于浮亏状态。
● 约 42 亿美元 FDV:市场隐含锚点(OTC 积分定价 + 社区约 25% 配额的反推)。
现实检验#1:FDV/TVL 比较
If the valuation of Lighter is set at approximately 5 times the TVL, then the resulting figure would be:
● 14.4 billion USD in TVL × 5 = approximately 7.2 billion USD in FDV
These numbers aren’t chosen arbitrarily; they represent the approximate value of similar platforms in the market.
● Hyperliquid: approximately 5.8 times FDV/TVL
● Aster: approximately 4.2 times FDV/TVL
Therefore, if Lighter can maintain its TVL and continue to prove itself as a platform with the highest trading volume, then an FDV of approximately 7 to 8 billion USD would be a reasonable “fair value” target.
Reality check #2: Income comparison ( imperfect, but important)
Income isn’t the only way to evaluate a platform in the crypto industry (narrative is equally important), but it’s one of the most reliable indicators of reality, allowing us to determine whether the use of the platform actually translates into cash flow.
Estimated annual income:
● Hyperliquid: approximately 900 million USD
● Aster: approximately 513 million USD
● Lighter: approximately 167 million USD
● dYdX: approximately 10.9 million USD
Two conclusions can be true at the same time:
1. There is indeed a gap in income levels between different platforms. Lighter’s current income is lower than that of Hyperliquid and Aster, which is a reasonable reason for the lower valuation given to Lighter today. If someone priced Lighter as the “next Hyperliquid,” then income would be a direct point of contention.
2. As a platform with no issued tokens and products that are not yet fully developed, this revenue is still quite solid. An annual revenue of ~168 million dollars is not “common”. It doesn’t automatically justify higher FDV, but it clearly shows that Lighter isn’t relying on hype to succeed, but rather on running a real, profitable business.
How should the valuation range be determined?
● Bear market/baseline (15–75 billion dollars in FDV):
As long as TVL remains stable and continues to demonstrate its leading position in terms of trading volume/OI, even if there are differences in revenue, this range is still viable.
● Bull market (75–125 billion dollars in FDV):
A catalyst is needed to become consensus. Specifically, this includes:
(a) faster revenue growth;
(b) higher and more sustainable activity levels; or
(c) mainstream distribution narratives that the market is willing to price in advance.
In short, revenue is a “proof point”. It puts pressure on short-term multiples, but it also indicates that Lighter already has real traction. The upside potential depends on whether revenue growth significantly increases after product expansion.
7. Scenario assumptions (a truly “reasonable” FDV range)
Bear market scenario: 15–42 billion dollars in FDV
Assumptions: weak market sentiment, heavy selling pressure from TGE, and lack of narrative support. Prices will remain around the VC floor or slightly above the implied value of tokens.
Baseline scenario: 42–75 billion dollars in FDV
Assumption: Pricing will be based on fundamental factors. The TVL will remain above $1 billion, and the volume/OH ratio will remain at a high level. Pricing will be done using comparable multiples.
In a bull market scenario, the value could range from $7.5 billion to $12.5 billion, including FDV.
Assumption: Catalysts will be agreed upon, including:
● Continued growth in RWA momentum and a clear path for RWA trading; and/or
● The Robinhood-style distribution model is widely accepted (even if not fully confirmed).
8. Roadmap signals: Why 2026 might be the year of true expansion.
Considering the overall product development timeline and narrative progression, 2026 seems to be a crucial year for Lighter’s expansion.
Deepening RWA efforts, expanding trading options, and improving mobile and portfolio margining features—these are not isolated functions, but rather part of a larger strategy aimed at enhancing distribution efficiency and liquidity.
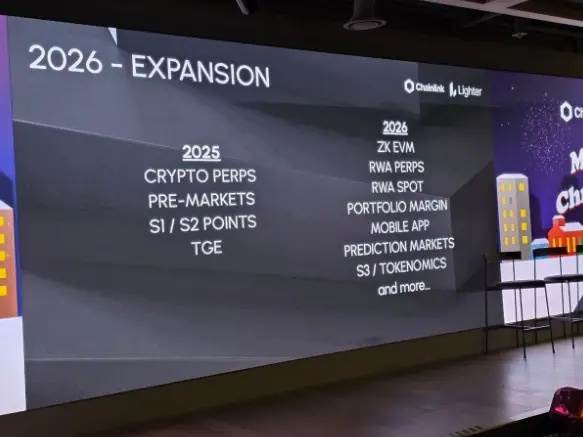
Lighter’s expansion roadmap for 2026 (Seoul offline event slides)
Lighter has shown significant traction in 2025, but what truly will change the valuation ceiling is what happens next.
At the Chainlink × Lighter Seoul meetup, a roadmap titled “2026 – Expansion” was shared, which included:
● ZK EVM
● RWA-related challenges
● RWA trading
● Portfolio margining
● Mobile applications
● Prediction markets
● S3 / 代币经济学
● ……以及更多
即便将其视为「在官方确认前的非正式信息」,当你把它与 Lighter 当下已验证的能力连接起来——稳定执行、快速交付、以及在 RWA 上的明确动能——这条方向线是高度自洽的。
为什么这条路线图对估值很重要
1)扩大产品面(TVL 与成交量的更多增长路径)
单靠永续合约就能把一个 DEX 做大;但加入现货,尤其是通向 RWA 现货的路径,会显著拓宽漏斗。
现货更「粘」、更利于 TVL 沉淀,也会吸引一类不以 50× 杠杆为核心的用户。
2)提升资本效率(组合保证金是关键)
组合保证金听起来不性感,但机构与专业交易者真正关心。
它让资金在不同仓位间协同工作、减少割裂,从而在不等比例增加新存款的情况下提升活跃度。
3)升级分发(移动端)
多数零售交易发生在手机上。
若 Lighter 想成为 Binance、Robinhood 这类「点一下就能交易」体验的可行替代,原生移动端不是加分项,而是直接的增长杠杆。
4)加码最强叙事(RWA)
RWA is not just a new market; it represents the most straightforward bridge towards addressing non-cryptocurrency-native needs. The roadmap clearly states that RWA Perps and RWA Spot are core strategies, not peripheral features.
Adding flexibility—predictive markets and “more” options—is also important.
Predictive markets have already proven their necessity in the crypto ecosystem.
By integrating these features into a larger trading platform, we can create a highly engaging new product line, thereby increasing user retention and keeping them within the same ecosystem.
9. Risks that require serious consideration:
● Market conditions: The total market value of cryptocurrencies is currently around $2.96 trillion, far below the historical peak of $4.27 trillion reached in October 2025. If macroeconomic conditions continue to deteriorate, trading volume across all cryptocurrencies will increase significantly.
● Market trends after TGE: There may be sellers in the market. The real challenge lies in whether TVL/trading volume can stabilize after initial user loss.
● Competition is real: Hyperliquid performs well in its field, and other platforms will soon replicate its functionality.
● Narrative and verification: Robinhood/RWA’s market approach can easily lead to controversies due to delays in implementing certain features.
Conclusion:
A simple way to evaluate the value of Lighter is to compare it to Hyperliquid. Once you choose a discount rate, the evaluation is complete.
A better approach is to recognize the differences between them:
● The scale has been achieved (TVL, sales volume, revenue).
● RWA appears to be a true wedge-shaped structure, rather than just a side project.
● The product strategy aims at broader markets (retail → spot trading → profit margins → new vertical sectors).
● Even if distribution through fintech/brokers becomes feasible, even if only partially, its ultimate limit cannot be “another cryptocurrency exchange”.
This is why I believe $1.5 billion is a bottom line. Around $4.2 billion represents the most clear market implied value. If TVL remains constant and catalysts continue to emerge, then the fair value should start above $7 billion.
This is how I think about segmentation (I’m not offering any advice, just my plan).
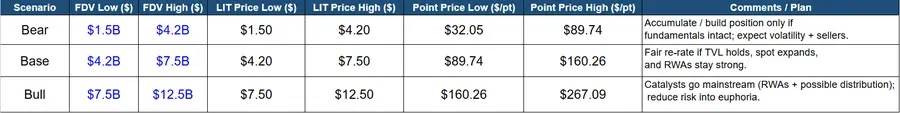
To maintain discipline, I treat FDV as a region, rather than a precise target.
In the bear market zone (between $1.5 billion and $4.2 billion), if prices fall after the TGE, I consider this to be an “opportunity zone”. Holding short positions in this area is the safest choice (less emotional pressure involved). For those who truly believe in this theory, this is the area with the clearest risk/reward ratio. The growth in TVL, trading volume, and RWA already proves this.
The benchmark range is between $4.2 billion and $7.5 billion. If Lighter can maintain its TVL and continue to operate on a large scale, I believe this price is reasonable. If the price really reaches this level, I would consider taking some profits (just to save some money), while still keeping my positions. Why? Because the development roadmap for 2026 includes elements that will help expand its value over time—such as risk-weighted assets, expansion of spot business, portfolio margin, mobile applications, etc.
The bull market range is between $7.5 billion and over $12.5 billion. This is the area where “catalysts become consensus”. If Lighter rises in this range, it likely means that there’s strong momentum in RWA, and/or the market starts to take distribution strategies seriously (collaboration with fintech companies/brokers). In such cases, I would be more willing to use this strength to reduce risks, as the cryptocurrency market can also experience excessive volatility and rapid reversals in this range.
In short: I don’t want to pursue extreme returns. I just want a plan that allows me to withstand market fluctuations, achieve profitable gains, and keep my positions even after Lighter’s performance continues into 2026.
Ecosystem briefing (Fuego NFT): If you want to participate more actively, check out @fuegonft: a community-driven NFT collection led by… @satoshiheist. Key details: 90% of the tokens will be deposited into Lighter’s LLP treasury to support the ecosystem.
How to get WL: Join Discord, stay active, create useful content, and support Lighter sincerely.